

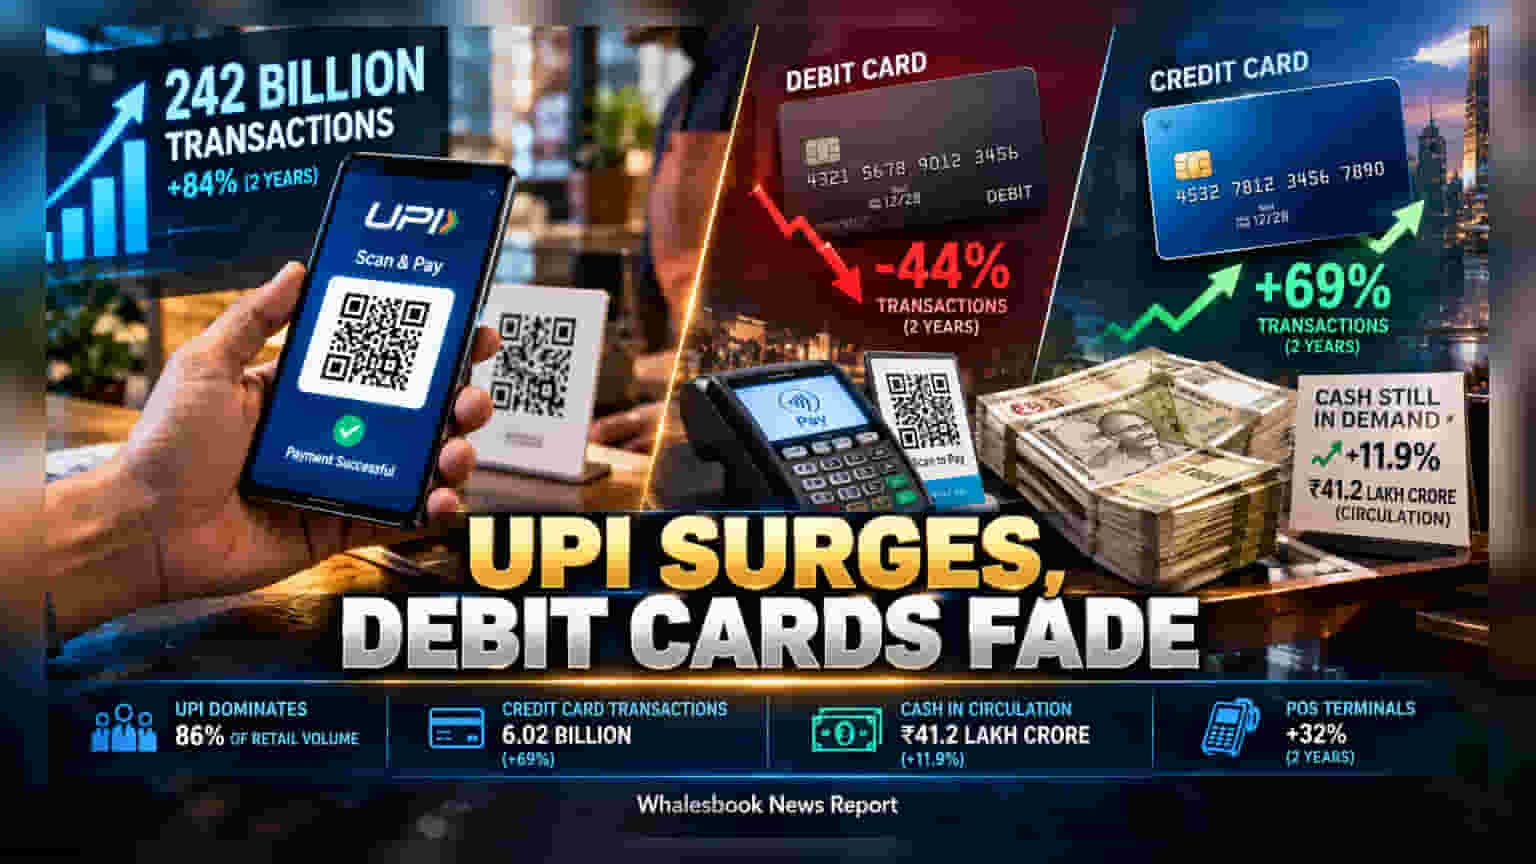
UPI transactions reached 242 billion in FY26, capturing 86% of retail payments. While credit card usage and cash circulation continue to rise, debit card transactions have fallen by 44%. This shift shows that consumers are using different payment methods for specific needs, which impacts how banks earn fee income and manage their services.
Payment habits in India are changing, with a clear divide between how people use digital and physical money. Official data for FY26 shows that Unified Payments Interface (UPI) has become the dominant method for daily small-value transactions, while debit cards are losing their relevance for shopping. At the same time, credit card usage is climbing, and demand for physical cash remains steady, highlighting a fragmented payment market.
UPI usage has grown significantly, reaching 242 billion transactions in FY26, an 84% increase from two years ago. It now accounts for about 86% of all retail payment volume. The average value per UPI transaction has dropped to ₹1,300, indicating that people are increasingly using the platform for everyday, smaller purchases. With the number of UPI QR codes doubling to 761 million over the last two years, this method has effectively captured the high-frequency, low-value payment segment.
In contrast, debit card usage has declined sharply. Despite there being over 1 billion debit cards in circulation, transactions using these cards for payments fell 44% in two years, dropping to 1.28 billion in FY26. On average, each debit card was used for only about 1.2 payment transactions throughout the entire year. This suggests that for many customers, a debit card has become a tool primarily for withdrawing cash at ATMs rather than for making purchases at stores.
Credit cards, however, are moving in the opposite direction. Transactions on credit cards reached 6.02 billion in FY26, a 69% increase over the two-year period. On average, each credit card was used 50 times during the year, showing much higher engagement than debit cards. This shift is notable for investors, as credit cards generally offer a different revenue model for banks compared to debit cards or UPI, which typically do not carry merchant fees in the same way.
Even with the surge in digital payments, cash has not disappeared. Banknotes in circulation rose 11.9% to ₹41.2 lakh crore by the end of March 2026. The Reserve Bank of India has identified this as a paradox where digital payments and cash demand grow together. Many people still use cash as a form of safety or for specific transactions where digital methods are less preferred. Point-of-sale terminal infrastructure has also continued to grow, expanding 32% over the last two years, which shows that card-accepting machines are still being deployed despite the decline in debit card payment volume.
For the Indian banking sector, these trends are important to monitor. The decline in debit card payments may affect fee-based income, while the rise in credit card usage presents growth opportunities. Investors may track how banks adapt their strategies to focus more on high-engagement credit products and whether they can continue to balance the cost of maintaining cash-handling infrastructure with the growth of digital payment platforms.