

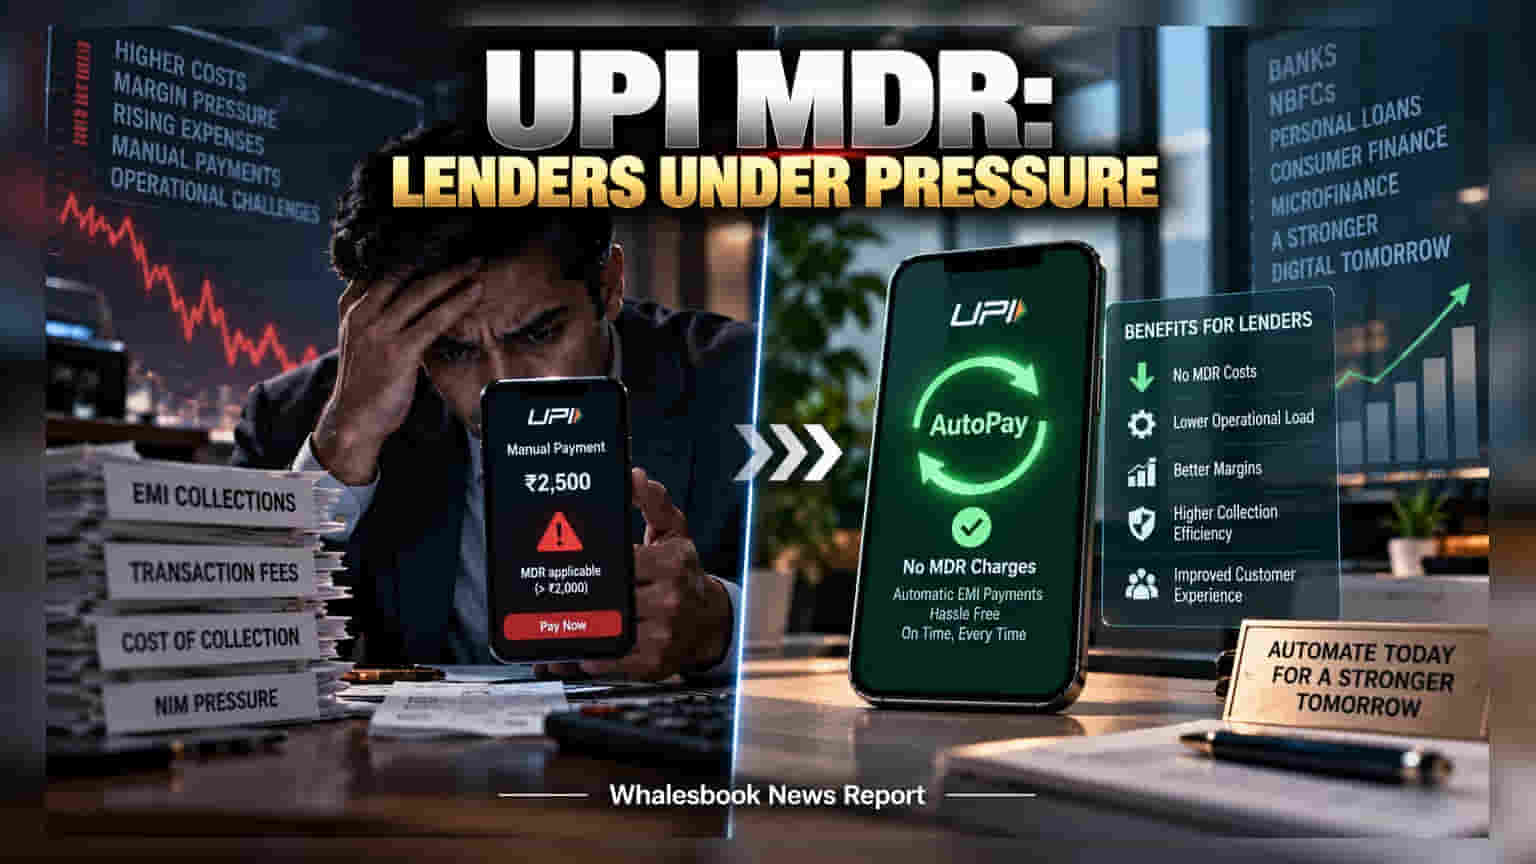
Manual UPI loan repayments exceeding ₹2,000 now attract transaction fees that lenders cannot pass to borrowers. To protect their profit margins, banks and NBFCs are aggressively moving customers to automated UPI mandates, which are exempt from these costs. Investors should monitor how quickly lenders can transition their portfolios to automated collection to minimize these operational expenses.
Financial institutions are facing a new cost structure for digital loan collections. When a borrower uses a manual UPI payment to pay an EMI or loan installment of over ₹2,000, the lender is now required to pay a Merchant Discount Rate (MDR) fee. Because regulatory guidelines and competitive pressure prevent banks and Non-Banking Financial Companies (NBFCs) from passing these transaction costs directly to the borrower, the expense is absorbed by the lending entity.
This creates a direct impact on the Net Interest Margins, which is the difference between the interest income a lender earns and the interest it pays out. For high-volume lenders, such as those providing personal loans, consumer durables, or microfinance, even small transaction fees can add up to a significant drag on profitability over time. The challenge is particularly acute for lenders that historically relied on manual monthly reminders and ad-hoc UPI transfers.
To mitigate this, financial institutions are aggressively pushing customers to adopt UPI AutoPay, also known as recurring mandates. According to updates from the National Payments Corporation of India (NPCI), these automated recurring transfers are exempt from the MDR charges. By moving the repayment process to an automated "standing instruction" model, lenders can bypass the transaction fees associated with manual payments.
From an investor perspective, this shift highlights the importance of digital infrastructure efficiency. A lender's ability to seamlessly migrate its customer base from manual, high-friction payment methods to automated mandates is now a key monitorable. While manual payments offer borrowers flexibility, they create operational inefficiencies for the lender. Successful lenders will be those who can incentivize this switch without creating customer dissatisfaction.
For investors, the key area to watch is the "cost of collection." Lenders that continue to see a high percentage of manual payments may face higher operating costs, which could lead to margin pressure if those costs are not managed effectively. The banking sector’s transition to automated collection is not just a technology upgrade; it is a defensive strategy to protect profitability in a landscape where transaction costs are increasingly being levied on the receiving merchant, including banks and NBFCs.