

Kerala-based Supra Pacific Financial Services plans to scale its network to 500 branches across 15 states in three years, aiming to grow its assets to ₹2,500 crore. The NBFC is focusing on gold loans and MSME credit to drive growth. Investors may monitor the execution risk associated with this rapid expansion and the impact on operational costs and profit margins.
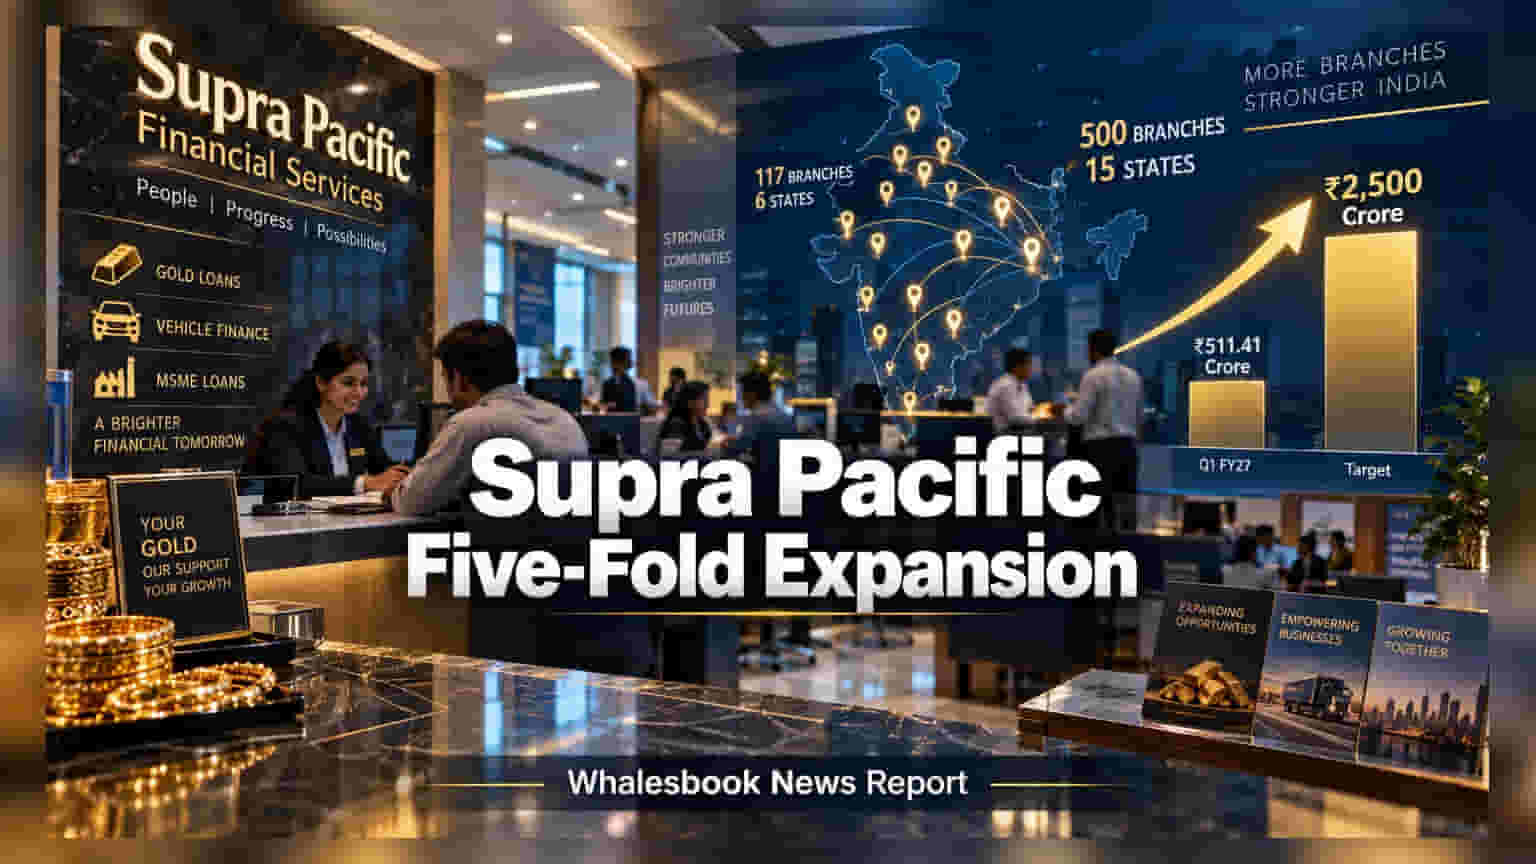
Supra Pacific Financial Services has announced an ambitious expansion plan to grow its branch network and asset base over the next three years. The Kerala-based non-banking financial company (NBFC) currently operates 117 branches across six states and plans to increase this to 500 branches spanning 15 states. Alongside this physical expansion, the company has set a target to increase its assets under management (AUM) to ₹2,500 crore, significantly higher than the ₹511.41 crore reported at the end of the first quarter of the 2026-27 fiscal year.
The firm's growth strategy centers on its gold loan business, which provides rapid, secured liquidity to borrowers. This segment is supported by a growing demand for gold-backed financing, which often allows for faster processing compared to unsecured personal loans. In addition to its core gold lending, the company is diversifying its portfolio by entering the vehicle finance market and providing secured working capital loans to micro, small, and medium enterprises (MSMEs) in the range of ₹10 lakh to ₹1 crore. This diversification is intended to broaden the company's revenue base beyond traditional gold loans.
Scaling operations from 117 to 500 branches involves significant operational challenges. For a smaller NBFC, rapid expansion requires substantial capital spending on infrastructure, technology, and hiring, which can exert pressure on profit margins in the short to medium term. Additionally, while gold loans are secured, they are sensitive to gold price volatility. A sharp decline in gold prices may affect the loan-to-value ratios and potentially increase the need for collateral top-ups from borrowers, which remains a standard monitorable for lenders in this sector.
The company has demonstrated rapid growth since 2020, with AUM rising from ₹21 crore in the 2020-21 fiscal year to ₹366 crore by June 2026. However, as the company moves into new territories outside its current strongholds of Kerala, Tamil Nadu, and Maharashtra, it will face competition from larger, established gold loan providers that often enjoy a lower cost of funds and deeper market penetration. Smaller NBFCs typically operate with a higher cost of borrowing compared to larger peers, which can influence interest margins. Success in this expansion phase will depend on the company's ability to maintain its asset quality while managing the risks inherent in rapid geographical scaling.
Investors may keep track of the company's quarterly results to assess whether the scaling of its branch network is translating into profitable growth. Key monitorables include the pace of new branch additions, the consistency of its loan book growth, the management of credit costs in the new MSME and vehicle finance segments, and the company's ability to secure funding at competitive rates to support its expansion targets.