

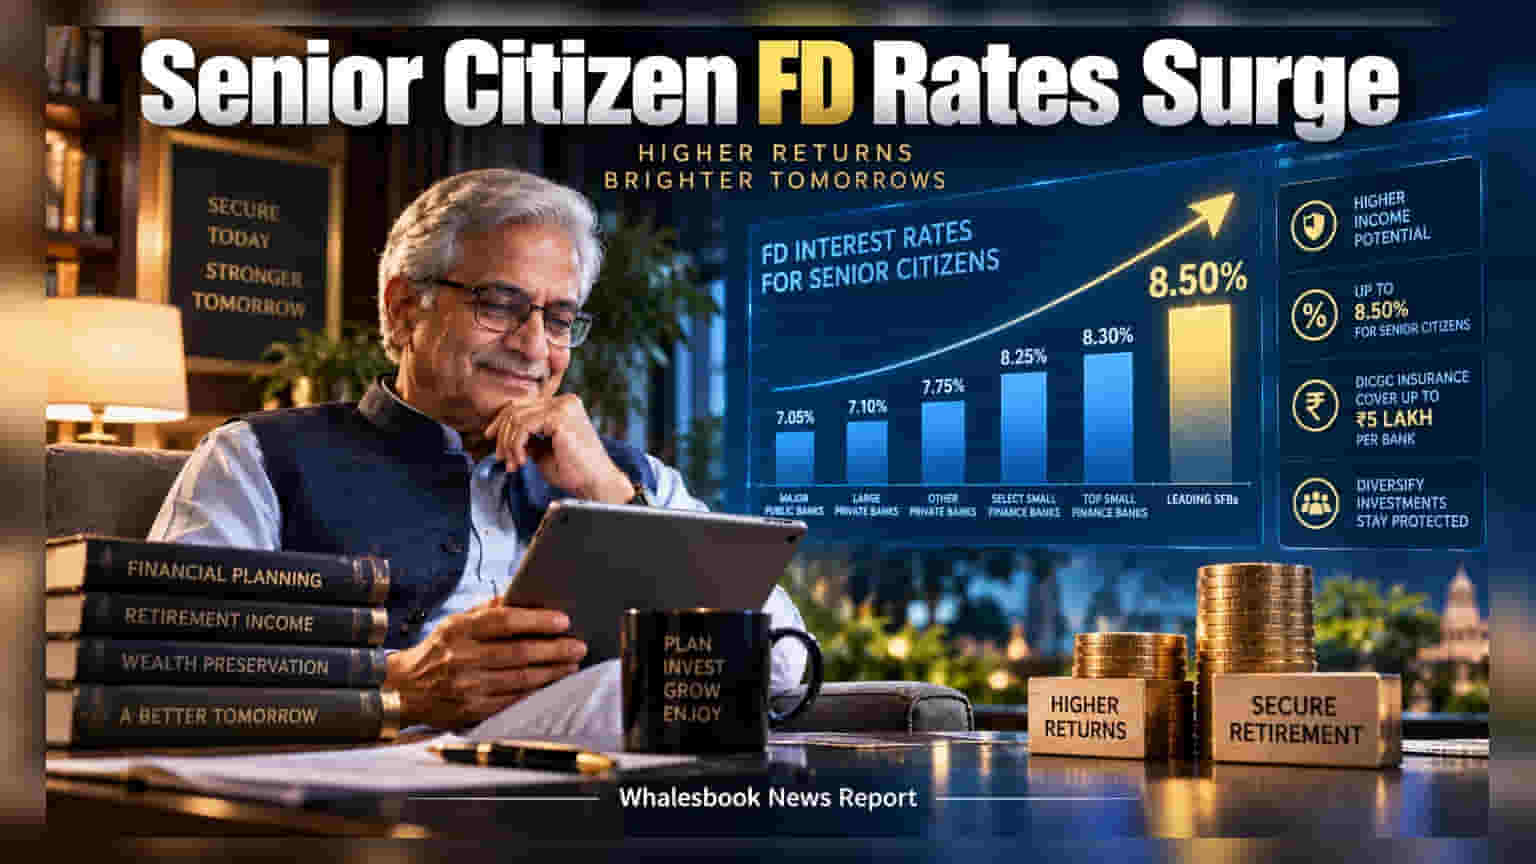
As of September 2026, several Small Finance Banks (SFBs) are offering senior citizens fixed deposit rates up to 8.50%, significantly higher than the 7.05-7.10% offered by major banks. While these returns are attractive for retirees, investors should balance higher yields with risk management. It is important to stay within the Rs 5 lakh DICGC insurance limit per bank to ensure capital protection while chasing these higher interest rates.
In September 2026, Indian retirees seeking higher income from fixed deposits are finding significantly better interest rates at small finance banks compared to traditional public and private sector lenders. While major commercial banks are currently offering senior citizens interest rates around 7.05 percent to 7.10 percent, specialized small finance banks are providing returns as high as 8.50 percent for similar tenures. This creates a notable yield gap for those prioritizing income generation over the brand size of their banking partner.
Equitas Small Finance Bank, ESAF Small Finance Bank, and Suryoday Small Finance Bank are currently among the leaders in this space, offering the 8.50 percent rate. Other institutions such as Jana Small Finance Bank and Ujjivan Small Finance Bank are providing rates up to 8.30 percent, while Shivalik Small Finance Bank and Utkarsh Small Finance Bank are closely positioned at 8.25 percent. In contrast, large private lenders like IndusInd Bank and YES Bank generally offer rates closer to 7.75 percent, with major national lenders providing the lowest yields in the current market.
This difference in interest rates exists because small finance banks often face a greater need to aggressively mobilize deposits to fund their lending operations, which are typically concentrated in micro-loans and unbanked segments. However, investors must recognize that higher interest rates often come with a different risk profile compared to larger, systemic banks. The primary protection available to individual depositors is the deposit insurance provided by the Deposit Insurance and Credit Guarantee Corporation, or DICGC. This insurance scheme covers the combined principal and interest of an investor up to a total of Rs 5 lakh per bank.
To manage risk while seeking these higher returns, investors may consider spreading their fixed deposit investments across multiple banks rather than concentrating all their funds in a single high-yielding institution. This diversification strategy helps ensure that if a specific lender faces financial difficulty, the total exposure remains within the insured limit. Additionally, investors should carefully check the specific terms regarding premature withdrawal. Penalties for breaking a fixed deposit early can often negate the benefits of the higher interest rate offered initially. Matching the chosen investment tenure with one’s expected personal liquidity requirements remains the most effective way to avoid these penalties and ensure financial flexibility.