

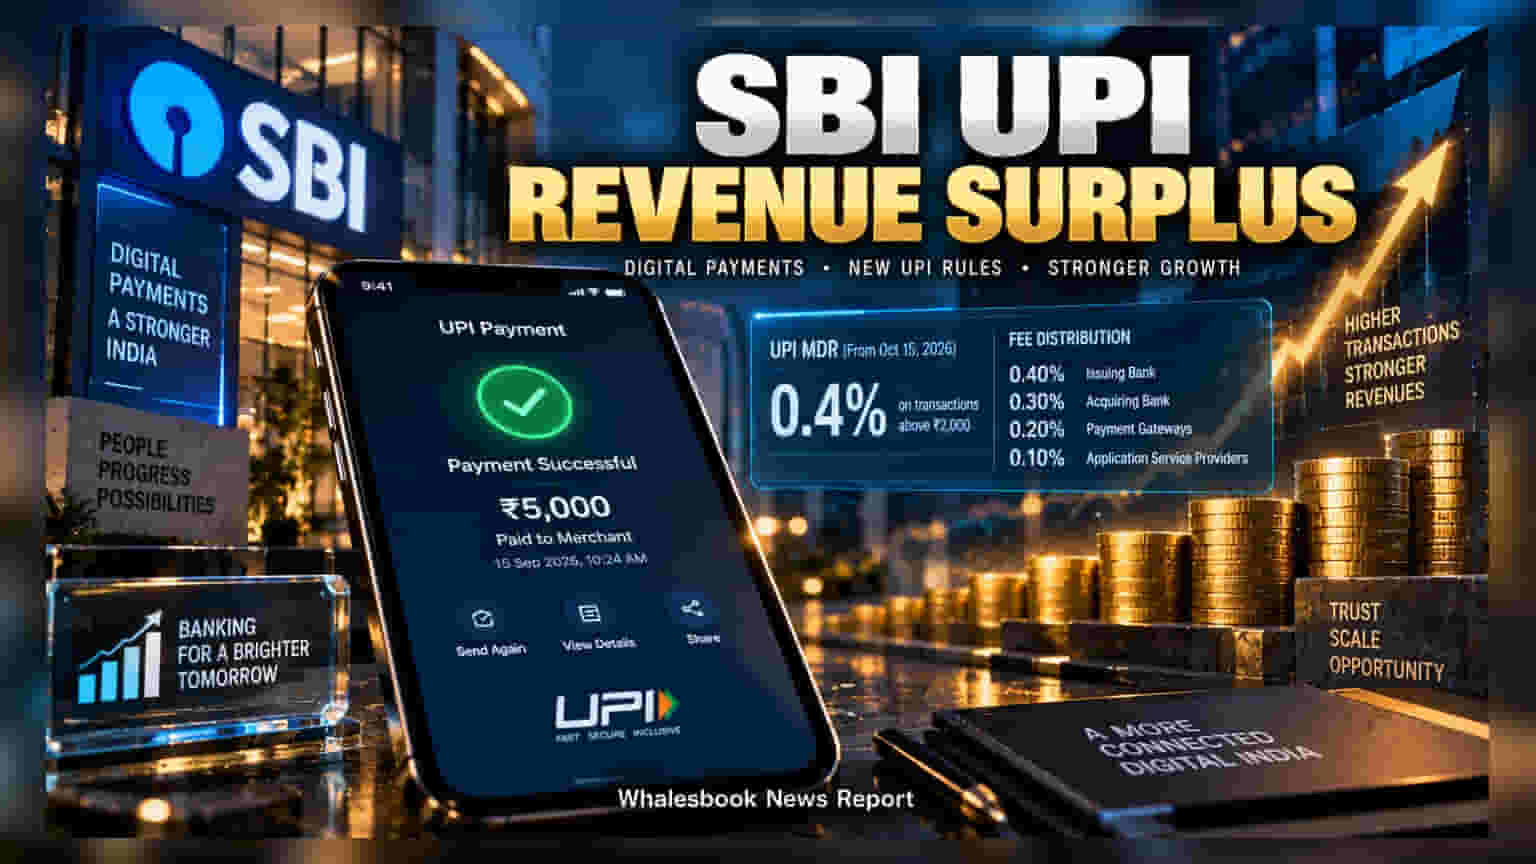
Starting October 15, 2026, State Bank of India will apply a merchant discount rate (MDR) of 0.4% on UPI transactions exceeding ₹2,000. This change is expected to create a new revenue stream for the bank, which functions as both an issuer and an acquirer. Investors should watch for potential shifts in consumer behavior, such as the splitting of transactions, which could impact volume trends.
State Bank of India (SBI) is preparing for a shift in its digital payment business as new regulatory rules for Unified Payments Interface (UPI) transactions take effect on October 15, 2026. Under the new framework, transactions exceeding ₹2,000 will be subject to a merchant discount rate (MDR) of 0.4%. This fee, paid by merchants for processing digital payments, is designed to support the costs associated with the digital payment ecosystem.
SBI holds a unique position in the Indian digital payment landscape. Because the bank operates as both a card issuer and an acquiring bank, as well as providing payment gateways and application services, it is well-placed to capture revenue at multiple stages of a transaction. The fee distribution is set to allocate 0.40% to the issuing bank, 0.30% to the acquiring bank, 0.20% to payment gateways, and 0.10% to application service providers. With its extensive market presence, SBI expects these charges to contribute to its fee-based income, though the bank is still finalizing calculations regarding the exact net surplus.
While this change offers a new revenue opportunity, it also introduces operational risks that the bank is monitoring. There is concern across the industry that consumers might alter their behavior to avoid the new charges. Specifically, users may choose to split larger payments into multiple smaller transactions of less than ₹2,000. While such a shift would increase the total number of transactions processed, it could put pressure on the underlying digital infrastructure without increasing the total value of payments. Management is currently balancing these potential systemic risks against the expected gains from the new fee structure.
Beyond the UPI fee update, SBI continues to maintain a strong liquidity position. The bank recently secured $10 billion through Foreign Currency Non-Resident (FCNR) accounts, which are interest-bearing deposits held by non-resident Indians in foreign currency. Coupled with an annual domestic deposit mobilization of ₹5.5 lakh crore, the bank appears to have a significant buffer to manage its capital needs. While smaller financial institutions might face pressure to shift their focus toward corporate lending to absorb liquidity, SBI’s current operational scale allows it to deploy capital efficiently across its diverse business segments.
For investors, the key monitoring points will be the actual revenue impact of the new UPI charges and whether there is a noticeable shift in transaction patterns. If consumers frequently split payments, the anticipated revenue gains might be lower than expected, and the strain on technical systems could rise. The bank’s ability to navigate these behavioral changes while maintaining its leadership in the digital payment space will remain an important area for shareholders to observe.