

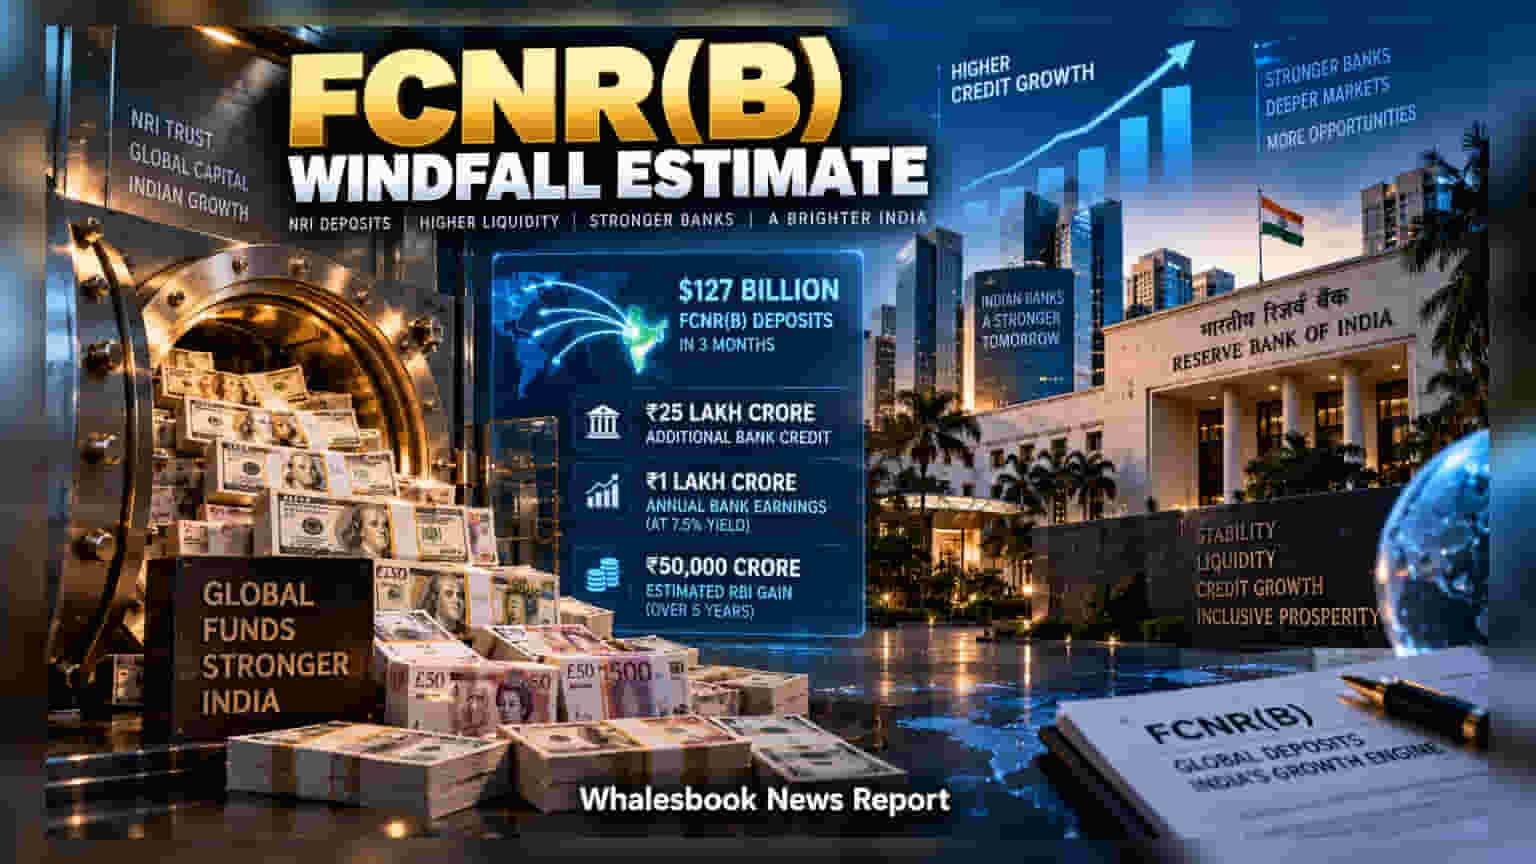
A new report from SBI Research estimates that recent $127 billion FCNR(B) deposit inflows could generate ₹5.5 lakh crore in gains for banks and the RBI. This liquidity potentially supports ₹25 lakh crore in new credit, though actual benefits depend on lending demand and market conditions.
A recent analysis by SBI Research highlights the potential economic impact of a surge in Foreign Currency Non-Resident (Bank) or FCNR(B) deposits. These are foreign currency accounts held by Non-Resident Indians (NRIs) in Indian banks. The report estimates that approximately $127 billion was mobilised through this scheme over a three-month period, marking one of the largest such inflows in recent years.
Boosting Bank Credit and Earnings
The additional liquidity generated by these deposits provides banks with funds that can be used for lending. According to the report, this influx could support around ₹25 lakh crore in incremental bank credit, or new loans. By lending these funds at an estimated yield of 7.5%, the report projects that banks could earn about ₹1 lakh crore in annual net interest income. Over a five-year period, this translates to a notional gain of roughly ₹5 lakh crore for the banking sector.
The Role of the Reserve Bank of India
The report also explores how the Reserve Bank of India (RBI) could benefit. It suggests that the RBI might invest a portion of these inflows, approximately $100 billion, in overseas assets with an expected annual return of around 4%. After accounting for hedging costs, which protect against currency fluctuations, the analysis projects a net gain of approximately ₹50,000 crore for the central bank over five years.
Understanding Currency Hedging
A key point raised by the report is the management of currency risk. FCNR(B) deposits are typically hedged using the RBI's swap mechanism. This process essentially locks in the exchange rate, allowing banks to avoid losses if the rupee depreciates against the foreign currency. The report argues that fears regarding currency volatility are often overstated because this hedging mechanism prevents direct losses on the underlying exposure.
What Investors Should Monitor
While the projections suggest a positive outcome for systemic liquidity and credit growth, the actual impact will depend on several moving parts. Investors may monitor future data on credit off-take, as the ₹25 lakh crore figure assumes that banks will successfully deploy this liquidity into new loans. Additionally, changes in interest rate environments and global market conditions could influence the returns earned on overseas assets and the demand for new credit. The report clarifies that these figures are estimates based on specific assumptions, and actual outcomes may vary depending on policy decisions and banking sector dynamics.