

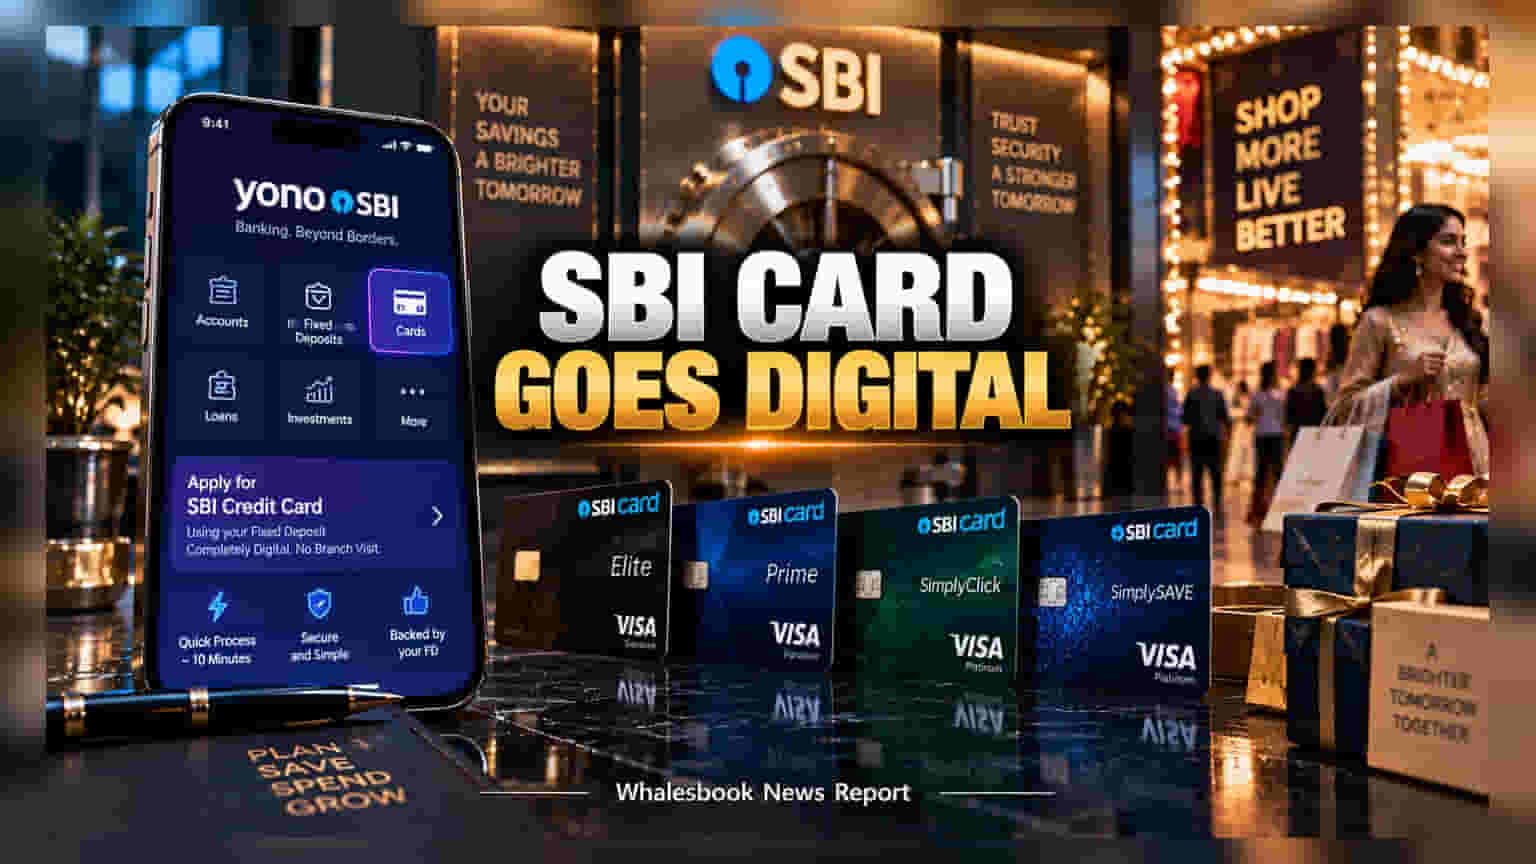
SBI Card has digitized the application process for FD-backed credit cards on the SBI YONO app, covering four variants including Elite and SimplyClick. This move aims to simplify entry for new credit users by using fixed deposits as collateral. While this improves accessibility, investors may watch for clarity on deposit requirements, fees, and credit limits to assess the product's long-term profitability and customer uptake.
SBI Card has integrated its secured credit card application process into the State Bank of India's (SBI) YONO mobile platform. This update allows customers with existing fixed deposits to apply for credit cards without visiting a bank branch, streamlining the process significantly. The facility now covers four popular card variants: SBI Card Elite, SBI Card Prime, SimplyClick SBI Card, and SimplySAVE SBI Card.
Secured credit cards are a strategic product segment for lenders because they act as an entry point for customers who may have limited or no credit history. By linking these cards to fixed deposits, the lender minimizes credit risk. If a cardholder defaults on payments, the bank has the security of the pledged deposit to recover the dues. For SBI Card, this strategy helps expand its reach into the customer base of its parent bank while maintaining a low-risk profile for these new accounts.
The shift to an end-to-end digital application on YONO is part of a wider trend in the Indian financial sector to reduce manual paperwork and processing time. The company has highlighted a 10-minute application turnaround time for eligible applicants. Increased digitization is generally viewed positively by analysts as it can lower operating expenses and improve the speed of onboarding, which is critical for growing retail portfolios efficiently.
However, market observers have noted that several key details are currently missing from the official communication. The company has not yet disclosed the minimum fixed deposit amount required to qualify for these cards, nor has it clarified how the credit limit is calculated relative to the pledged deposit value. Furthermore, the absence of information regarding joining fees, annual maintenance charges, and specific reward structures leaves customers and potential investors waiting for clarity. These cost factors are essential to understanding the actual value proposition for the consumer and the potential revenue impact for the company.
The Indian credit card market is increasingly competitive, with several private sector lenders, such as ICICI Bank and Axis Bank, already offering secured credit cards to tap into the new-to-credit segment. SBI Card’s success in this initiative will depend on how competitively it structures its offerings compared to peers and whether it introduces seasonal incentives or fee waivers to attract users.
For investors, the key monitorables will be the adoption rate of this digital-first product and its impact on the bank's customer acquisition costs. Future updates on the fee structure and the bank's strategy to cross-sell additional financial products to these new cardholders will be important. Investors will also watch to see if this digital model leads to a sustainable increase in the company's market share within the secured credit card space.