

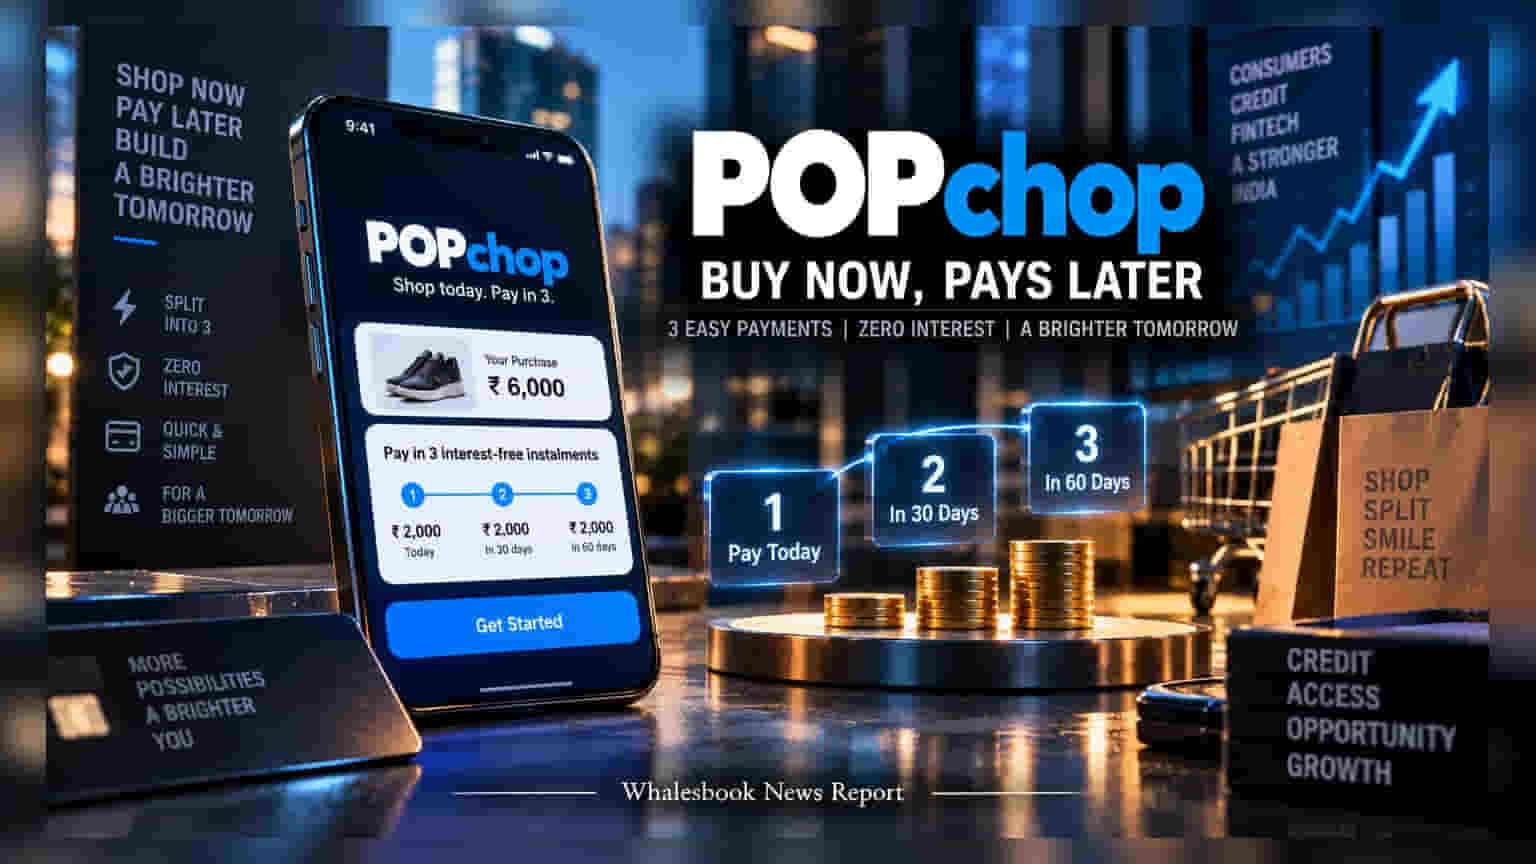
Fintech startup POP, backed by Razorpay, has launched a Buy Now, Pay Later (BNPL) service called POPchop, allowing users to split purchases into three interest-free installments. The launch marks a pivot toward credit-led monetization for the firm. While the company aims to tap into the younger, first-time borrower segment through lending partnerships, it faces intense competition from established players like CRED and Navi.
POP, a fintech platform backed by Razorpay, has introduced a Buy Now, Pay Later (BNPL) product called POPchop. The service allows users to divide their shopping expenses into three equal, interest-free installments. This launch represents a significant shift in strategy for the company, moving from a rewards-focused business model to formal credit services as it seeks to monetize its existing UPI-based user base.
The business model for POPchop relies on lending partnerships with regulated entities such as PayU Finance and LazyPay. In this arrangement, these partners handle the credit underwriting and limit assessment, while POP acts as the customer-facing interface. This structure allows POP to offer credit products without carrying the entire loan risk on its own balance sheet, though the company remains dependent on its partners' systems for credit approval and recovery.
Targeting a younger demographic, the company has noted that a significant portion of its early adopters are accessing formal credit for the first time. This approach aims to address a segment often underserved by traditional banking institutions, which typically require established credit histories. While the initial adoption metrics appear positive, the core challenge for the platform will be managing repayment consistency as it scales the product to a broader user base.
The Indian fintech sector has seen a strong shift toward credit as the primary path to profitability. Pure payment aggregation often provides thin margins, pushing platforms to explore high-margin lending products. However, the company faces significant competition in the retail credit space from established names like CRED and Navi, both of which are aggressively expanding their user bases.
For investors, the next monitorable will be the quality of the loan book and delinquency rates. As the company expands beyond early adopters, keeping default rates in check will be essential to sustain the business model. Furthermore, the platform must navigate the regulatory landscape for digital lending in India, which requires high transparency in fees and credit reporting. POP, which secured 30 million in funding last year, now faces the task of proving that its credit strategy can generate sustainable revenue while effectively managing the risks inherent in unsecured retail lending.