

India’s private life insurers showed mixed results for the first quarter of FY27. SBI Life drove growth through strong volume, while ICICI Prudential Life focused on margin improvement. Investors are now watching how these companies manage their heavy reliance on bank branches for sales amid evolving regulatory scrutiny on distribution models.
The first quarter of the 2027 fiscal year highlights a clear split in strategy among India’s top three private life insurers. While all three firms are fighting for market share, their results reveal different priorities: aggressive volume expansion versus profitability.
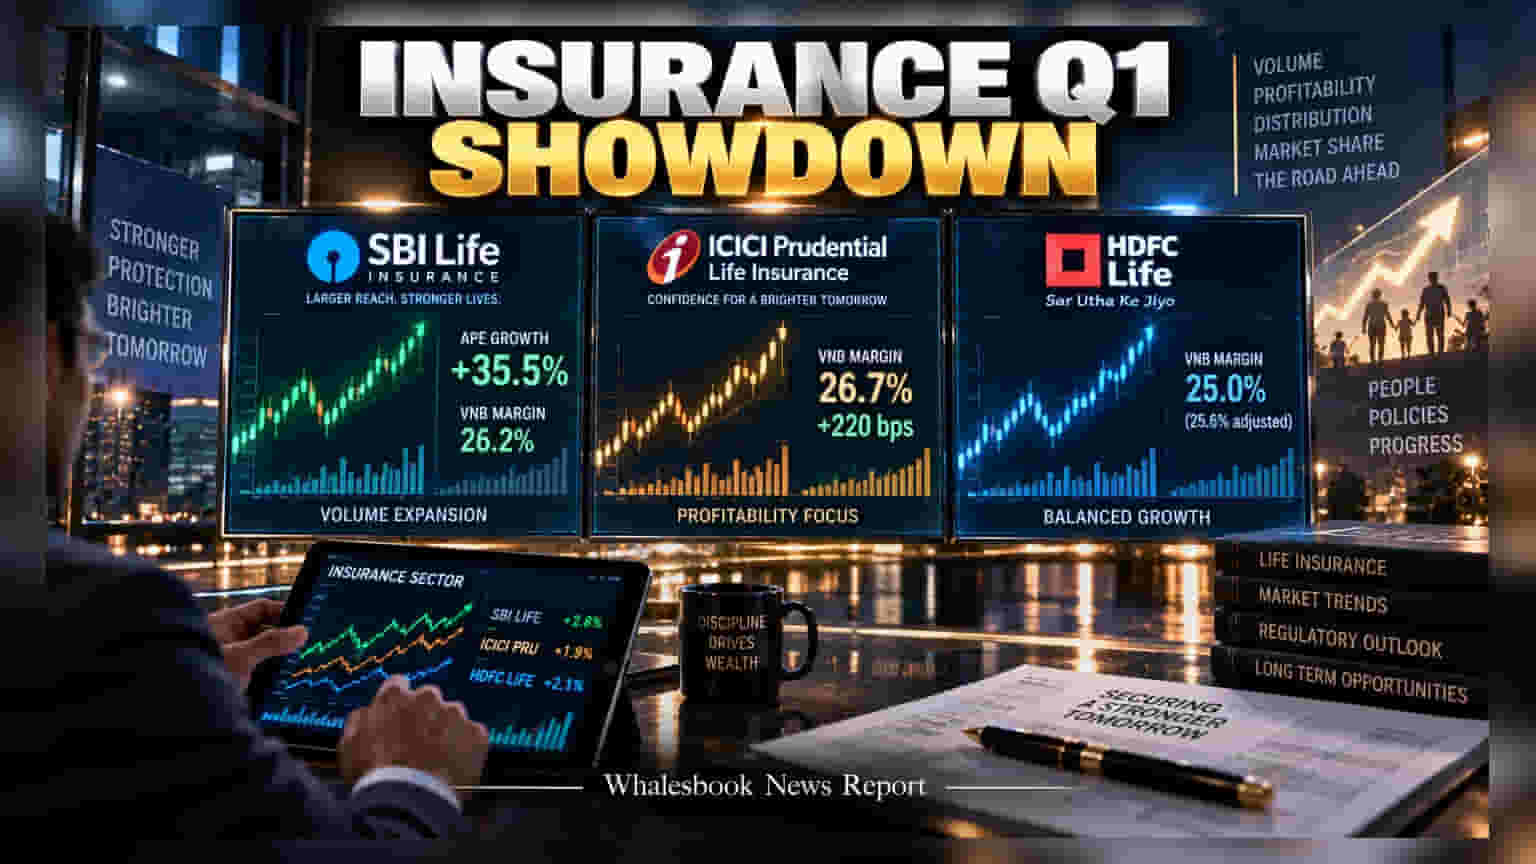
SBI Life Insurance led the sector in terms of volume, recording a 35.5 percent increase in Annualized Premium Equivalent (APE) compared to the same period last year. APE is a standard industry measure that represents the total value of new business by annualizing single premium policies. This strong performance was driven largely by the company's expansion into the group protection segment. However, this growth came at a slight cost, with profit margins on new business settling at 26.2 percent. As the company pushes for volume, investors may monitor whether it can maintain or improve these margins in upcoming quarters.
ICICI Prudential Life Insurance took a different path, prioritizing profitability. The company reported a Value of New Business (VNB) margin of 26.7 percent, the highest among its main peers, marking a 220 basis point improvement. This suggests that while volume growth is important, the company is successfully focusing on selling higher-value products to boost efficiency. This performance is notable as the sector faces broad challenges, including the impact of GST implementation on operational costs.
HDFC Life has maintained a more balanced approach, reporting a 25 percent margin, which reflects a steady mix of products. When adjusting for specific tax impacts, the underlying performance was slightly higher at 25.6 percent. A key challenge for the entire sector remains the reliance on bancassurance, which is the model of selling insurance products through bank branches.
Regulatory bodies have been increasingly focused on how insurers distribute their products to prevent potential conflicts of interest. SBI Life has taken steps to diversify its distribution, reducing its reliance on the parent bank, the State Bank of India, to about 47 percent of its total premium. In contrast, HDFC Life continues to carry a heavier dependency on its banking partner for individual premium sales. This creates a specific risk factor for shareholders: if regulators place tighter caps on how much business an insurance company can source from its partner bank, those with higher dependency could face more pressure to find new sales channels. Investors may keep a close watch on how these firms build out independent distribution networks to reduce these risks.