

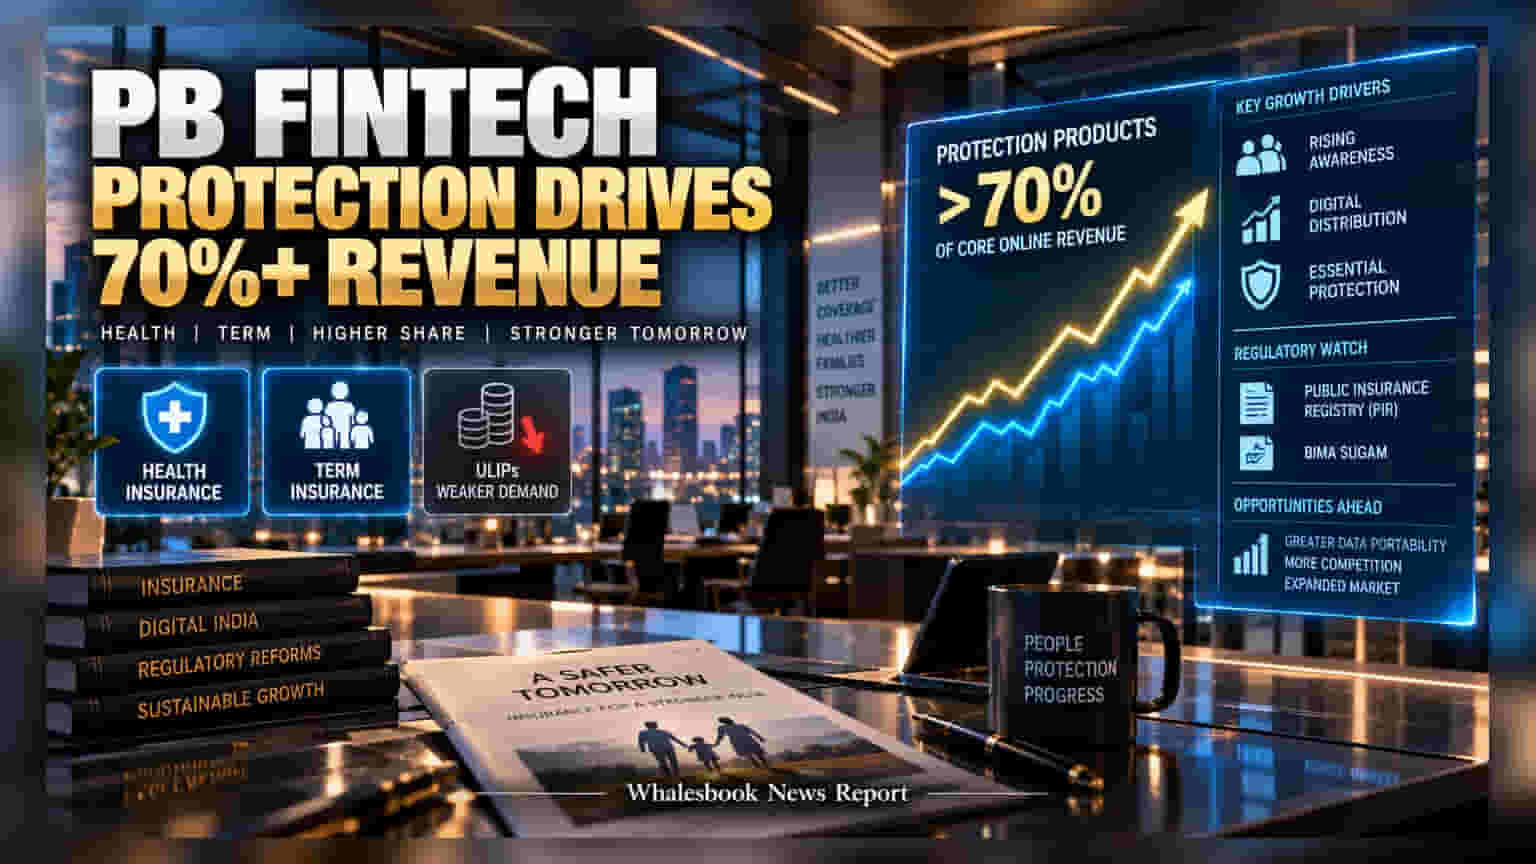
PB Fintech reports that protection products like health and term insurance now make up over 70% of its core online revenue. While the firm expands in these areas, it faces a slowdown in savings-linked plans. Investors should monitor how upcoming regulatory changes like the Public Insurance Registry impact future commission structures and distribution costs.
PB Fintech, the parent company of the insurance aggregator Policybazaar, is seeing a significant shift in its business mix. The company has announced that protection-oriented products, specifically health and term insurance, now account for more than 70% of its core online revenue. This pivot highlights the company's reliance on essential insurance products as it navigates changing consumer demand.
While the protection category is growing, the firm faces challenges in other segments. Demand for savings-linked products, such as Unit Linked Insurance Plans (ULIPs), has seen weakness over the last two years. The company attributes this to stagnant market performance, which has made it difficult to attract new buyers for these investment-heavy products compared to their core protection offerings.
Looking ahead, the company is closely watching new initiatives from the Insurance Regulatory and Development Authority of India (IRDAI). Two major projects are currently in focus: the Public Insurance Registry (PIR) and Bima Sugam. The Public Insurance Registry is designed to improve data portability, which would allow customer history and KYC data to be shared more easily across the industry. Currently, this data is often locked within individual insurer systems, creating a fragmented experience. If successful, the registry could simplify the process for consumers switching providers, potentially increasing competition.
Investors should also note the ongoing discussion regarding Bima Sugam, an initiative aimed at standardizing digital infrastructure for insurance in India. There is uncertainty regarding how these regulations will affect distribution costs and potential fee caps. While some may view digital platforms as low-cost, the company emphasizes that acquiring customers for complex products like health insurance requires significant investment in awareness and advisory services. High-quality advice remains a critical part of their model.
The key risk for the company lies in how future regulations shape commission structures and payouts. Because the business relies on distribution, any regulatory change that limits fees or mandates different payout structures could pressure profit margins. Additionally, the company must continue to manage high customer acquisition costs, which remain a reality for digital distribution despite technological efficiencies.
For investors, the primary monitorables include the final guidelines on the Public Insurance Registry and Bima Sugam, as well as the company’s ability to maintain its profit margins while growing its protection-product portfolio. Tracking how these regulatory updates influence the competitive landscape and industry commission norms will be essential for understanding the company's long-term earnings potential.