

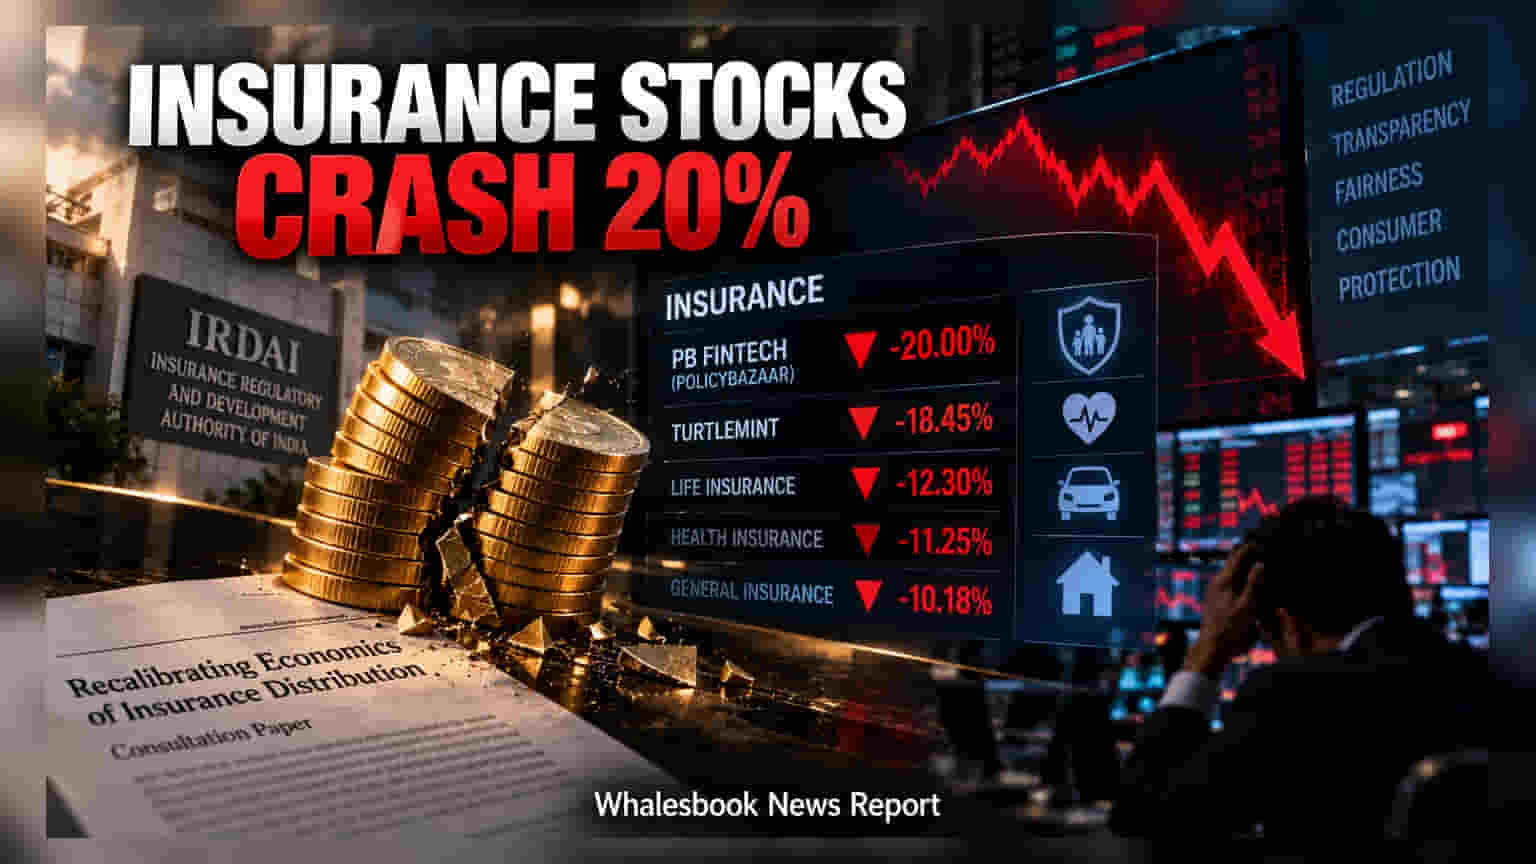
Shares of PB Fintech hit the 20% lower circuit on September 24 following the IRDAI's draft plan to cap insurance commission payouts. The proposal targets key segments like life, health, and motor insurance. Investors are concerned about the potential impact on the earnings of major online insurance aggregators, which rely heavily on commission-based revenue models.
Shares of PB Fintech, the parent company of Policybazaar, dropped 20% to reach the lower circuit on September 24. This market movement followed the release of a consultation paper by the Insurance Regulatory and Development Authority of India (IRDAI) titled 'Recalibrating Economics of Insurance Distribution'. The regulator's draft proposes strict caps on the commissions paid by insurance companies to distributors, which could change how businesses like PB Fintech and Turtlemint generate revenue.
Impact on Insurance Distribution Models
Insurance aggregators operate by earning a commission from insurance companies for every policy they sell to customers. The IRDAI proposal aims to reform this by placing ceilings on these payouts. The draft suggests capping first-year commissions for life insurance policies between 5% and 20%, depending on the length of the policy. For health insurance, it proposes limiting commissions to a range of 15% to 20%.
Furthermore, the proposal targets motor insurance, specifically suggesting that commissions for mandatory third-party covers should be significantly reduced or kept negligible. Because digital platforms drive high volumes through motor and health insurance, a cap on these commissions directly affects their ability to earn revenue on every sale. If the commission rates are forced downward, these companies may face pressure on their profit margins unless they can increase their sales volume or diversify their revenue streams significantly.
Regulatory Goal and Market Uncertainty
The IRDAI’s stated objective is to prioritize product transparency, reduce the likelihood of mis-selling, and simplify insurance products for the average consumer. By linking commission payouts to the actual effort required to sell a product rather than just the volume of sales, the regulator hopes to create a more stable and consumer-focused environment. However, for investors, the immediate concern is the transition period and the potential reduction in take-home revenue for large distribution platforms.
Another significant point in the proposal is the restriction on bundling insurance products with credit, which has historically been a tool for increasing sales figures for many distributors. The regulator has opened this draft for public feedback until October 25. Until the final regulations are notified, the specific impact on each company remains an estimate, leaving investors to monitor how these intermediaries adjust their operational costs and business strategies to maintain profitability under a more regulated commission framework.