

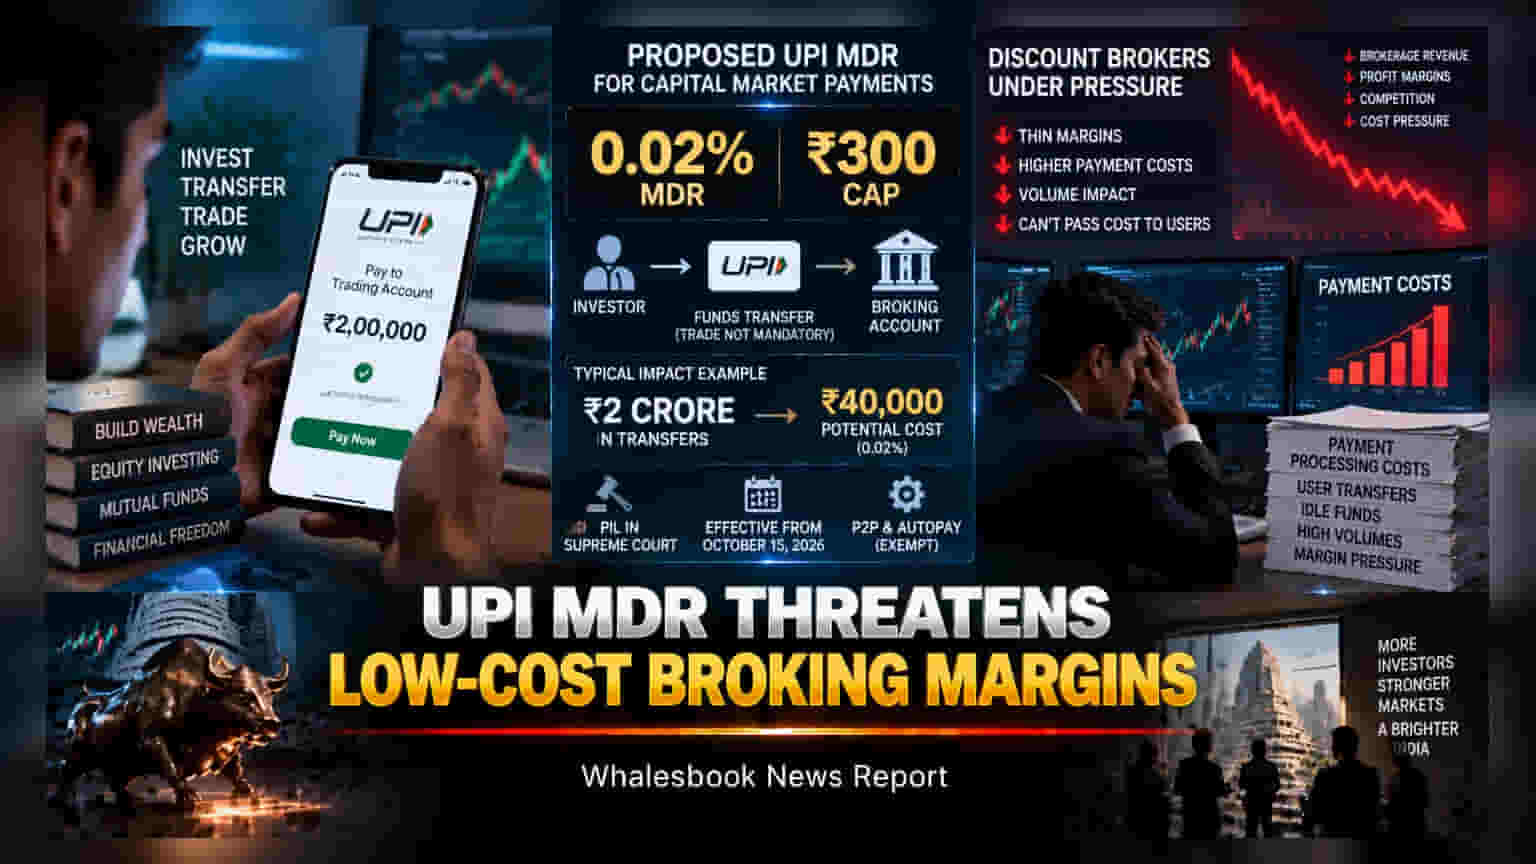
Starting October 15, 2026, capital market UPI transactions will attract a 0.02% merchant discount rate, capped at ₹300. While the fee is small, discount brokers warn it could pressure profit margins because they cannot pass this cost to clients, particularly on funds that do not lead to trades. A legal challenge against the framework is also currently pending in the Supreme Court.
The National Payments Corporation of India (NPCI) has announced a new Merchant Discount Rate (MDR) framework for UPI transactions, which is set to take effect on October 15, 2026. Under the new rules, capital market transactions—including transfers made to stockbrokers, mutual fund houses, and securities platforms—will be subject to a 0.02% fee, capped at ₹300 per transaction. This sits alongside a separate 0.4% MDR for standard merchant payments exceeding ₹2,000.
The core issue facing the brokerage industry involves the structure of these payments. Unlike a standard retail purchase where a customer buys a product, transferring money into a broking account does not guarantee that a trade will follow. Discount brokers, who operate on thin profit margins, are concerned that they will have to bear this 0.02% charge on every UPI transfer, regardless of whether the client eventually executes a stock market order. Industry leaders, including those from Zerodha and Choice Broking, have noted that because brokers are unable to pass this cost directly to the end user under the current proposal, it could directly impact the profitability of low-cost brokerage models.
The potential for cumulative costs is high for platforms that handle large volumes of retail transactions. If a customer frequently moves money into their account but trades sparingly, the broker effectively pays a fee for holding these idle funds. While the percentage is low, the cumulative effect of thousands of such transactions could create a financial hurdle for brokers who do not charge high fees for their services.
There is also a broader legal and regulatory dimension to this development. A Public Interest Litigation (PIL) has already been filed in the Supreme Court of India, challenging the validity and implementation of the new MDR framework. Investors and market observers are watching this legal proceeding closely, as any potential court-ordered stay or modification could alter how these fees are applied or whether they remain in place.
However, the impact on investors may remain limited in certain areas. Crucially, the framework exempts Person-to-Person (P2P) transfers and UPI AutoPay mandates. This means that recurring investments like Systematic Investment Plans (SIPs) will not attract this MDR, providing some relief for regular, long-term investors. The primary monitorable for shareholders and market participants in the coming weeks will be the Supreme Court’s stance on the pending litigation and any subsequent clarifications or operational adjustments issued by the NPCI or the brokerage industry regarding fund transfers.