

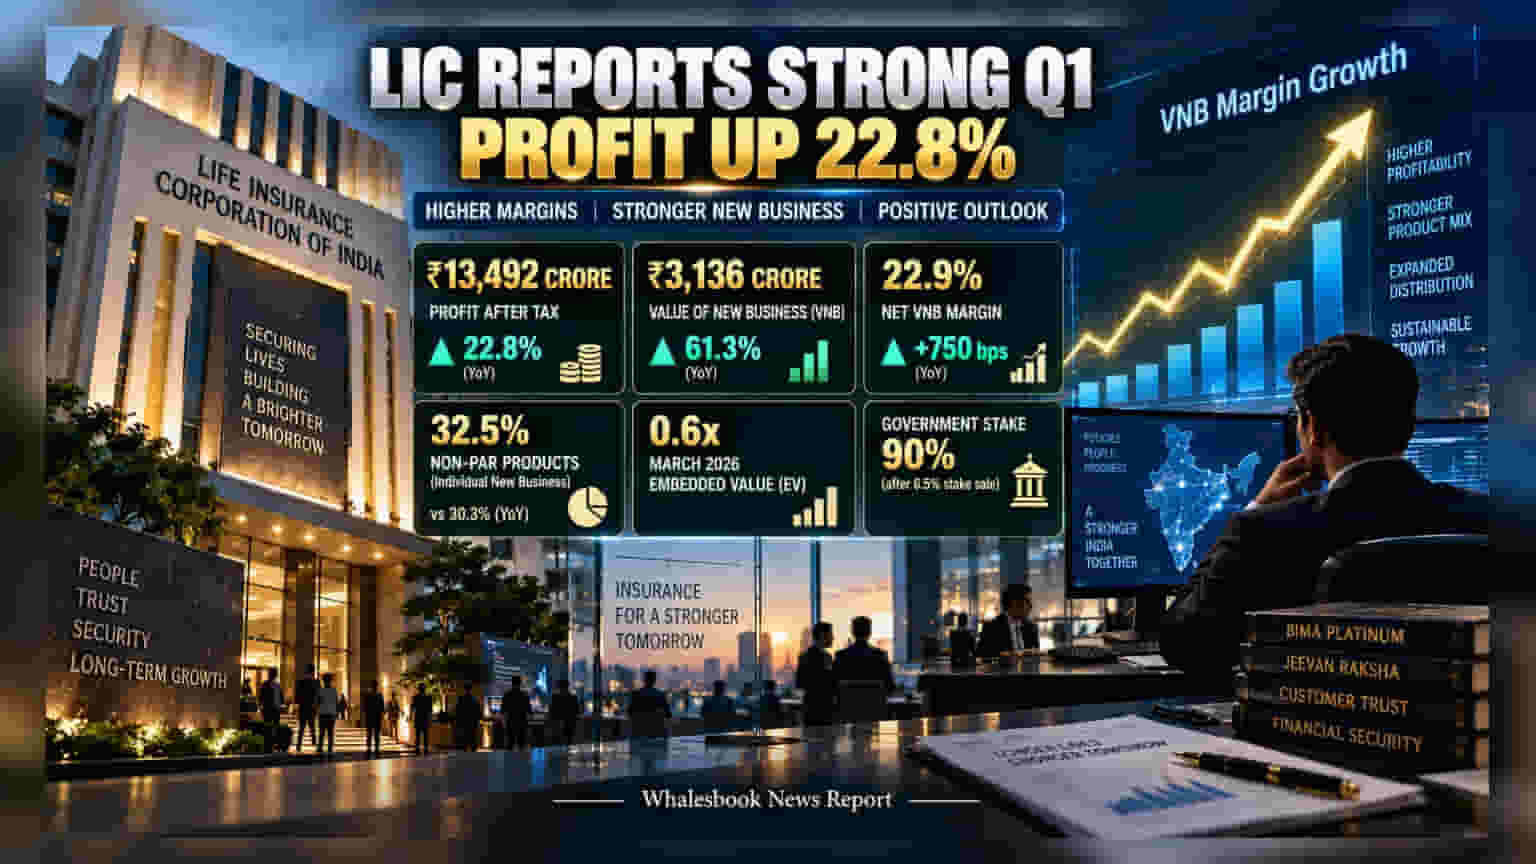
LIC of India reported a strong Q1 FY27 with a 22.8% rise in profit to ₹13,492 crore and a 750 basis point jump in profit margins. Investors are watching the insurer's shift toward high-margin products and the reduction in government stake, which may support a potential valuation re-rating compared to private rivals.
Life Insurance Corporation of India (LIC) has reported a robust start to the 2027 fiscal year, with profit after tax rising 22.8% year-on-year to ₹13,492 crore in the first quarter ending June 30, 2026. This performance was driven by a significant 61.3% jump in the Value of New Business (VNB)—a measure of the expected profit from new policies sold—which reached ₹3,136 crore.
A key driver of this improvement is the company’s strategic shift in product mix. LIC has been aggressively increasing the share of non-participating (non-par) products, which are policies that do not share profits with customers and typically offer fixed returns. These products are more profitable for the insurer. In Q1 FY27, non-par products accounted for 32.5% of individual new business, an improvement from 30.3% in the same period the previous year. This pivot helped boost the net VNB margin by 750 basis points, reaching 22.9% for the quarter.
Valuation and Government Stake
For investors, the primary area of focus has been the company’s valuation relative to its private sector peers. Historically, LIC has traded at a discount, with recent data showing the stock valued at roughly 0.6 times its March 2026 Embedded Value (EV), which is a metric representing the total worth of the company's existing business. The government’s recent 6.5% stake sale, which reduced its holding to 90%, has addressed concerns about a large supply of shares entering the market. With this supply-side pressure removed, market participants are watching to see if the stock’s valuation will move closer to private insurers as the company demonstrates improved operational efficiency.
Risks and Market Challenges
Despite the positive trend, investors remain cautious about several execution risks. Maintaining the current shift toward non-par products depends heavily on whether customer demand stays steady. If consumer preference swings back toward traditional products or unit-linked insurance plans (ULIPs), which are tied to market performance, the company’s profit margins could face pressure. Furthermore, the insurance sector is facing intense competition from private players who are often faster to adapt to digital distribution channels. LIC also navigates regulatory risks, including potential changes in tax treatment for insurance products and future updates to risk-based capital norms, which dictate how much capital an insurer must hold against its liabilities.
Looking ahead, the company’s ability to sustain this margin expansion will be a critical monitorable. Management has recently launched new offerings such as 'Bima Platinum' and 'Jeevan Raksha' in September 2026 to coincide with its 70th anniversary. The success of these products, combined with the insurer's massive distribution network of over 14 lakh agents, will determine whether the current momentum in new business premium can continue throughout the remainder of the fiscal year.