

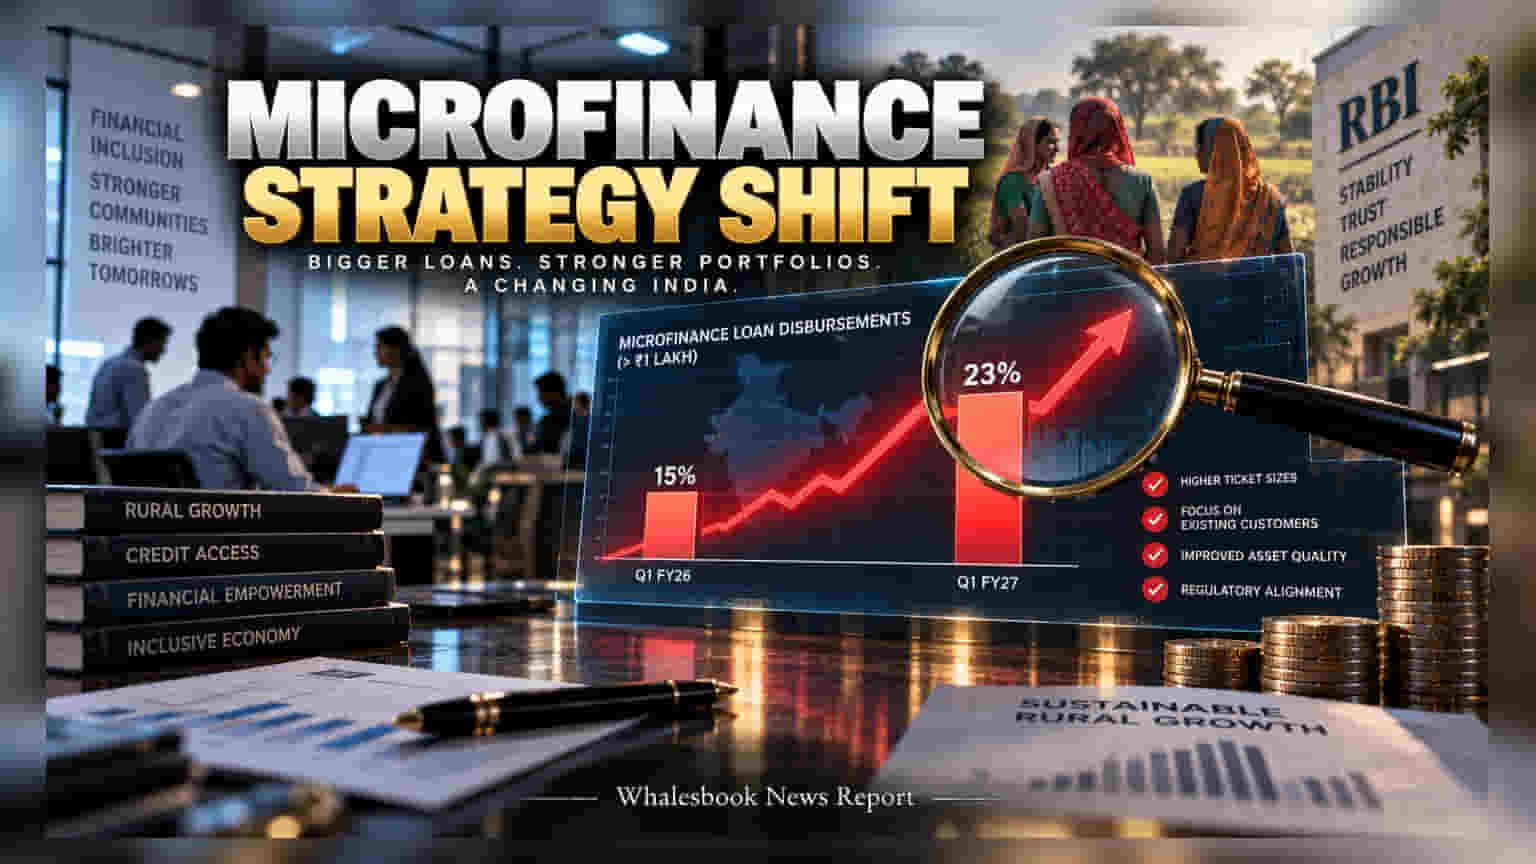
Microfinance lenders are pivoting away from small-ticket loans, with disbursements above Rs 1 lakh rising to 23% in the recent quarter. This strategic change aims to reduce high delinquency rates seen with new, unvetted borrowers. Investors should watch if this move effectively lowers defaults or if it increases the risk of debt traps for rural households.
The microfinance sector is undergoing a major change in how it distributes credit. Recent industry data shows a clear shift, with loans exceeding Rs 1 lakh now accounting for 23 percent of total disbursements during the April-June quarter. This is a significant jump from 15 percent in the same period last year. Simultaneously, lenders are reducing their focus on small-ticket loans of Rs 50,000 or less, a segment that previously drove volume but often resulted in higher repayment issues.
Why Lenders Are Changing Strategy
Historically, microfinance institutions relied on high-volume, small-ticket lending to expand their reach. However, this strategy often involved onboarding new borrowers with little to no formal credit history. When these borrowers struggled to repay, the lender’s delinquency rates—or the percentage of unpaid loans—would spike. By shifting toward larger loans, institutions are targeting existing customers who have demonstrated a track record of repayment. This approach is intended to provide a cleaner portfolio and protect profit margins from the volatility associated with high-risk, unproven borrowers.
Operational Efficiency and RBI Scrutiny
There is also an operational aspect to this shift. Servicing larger loans typically reduces the cost per unit of credit for the institution, allowing them to manage their expenses more efficiently. At the same time, this pivot aligns with the broader regulatory environment. The Reserve Bank of India (RBI) has been paying closer attention to the issue of over-indebtedness in the microfinance sector. By exercising greater selectivity and avoiding the mass-onboarding of new, potentially over-leveraged borrowers, lenders are trying to align their business models with stricter regulatory expectations regarding responsible lending.
Risks and Investor Monitorables
While this change may help improve asset quality, it is not without risk. The primary concern is borrower leverage. As institutions increase the size of individual loans, there is a risk that rural households could become over-leveraged if they take on debt beyond their actual repayment capacity. If these borrowers struggle to repay, the impact on lenders could be more severe because the individual loan amounts are larger. Investors should monitor the non-performing asset (NPA) ratios and the repayment trends for these larger loan portfolios in the coming quarters. It will be important to track whether this strategy successfully lowers long-term default rates or if it simply shifts the nature of risk within the sector.