

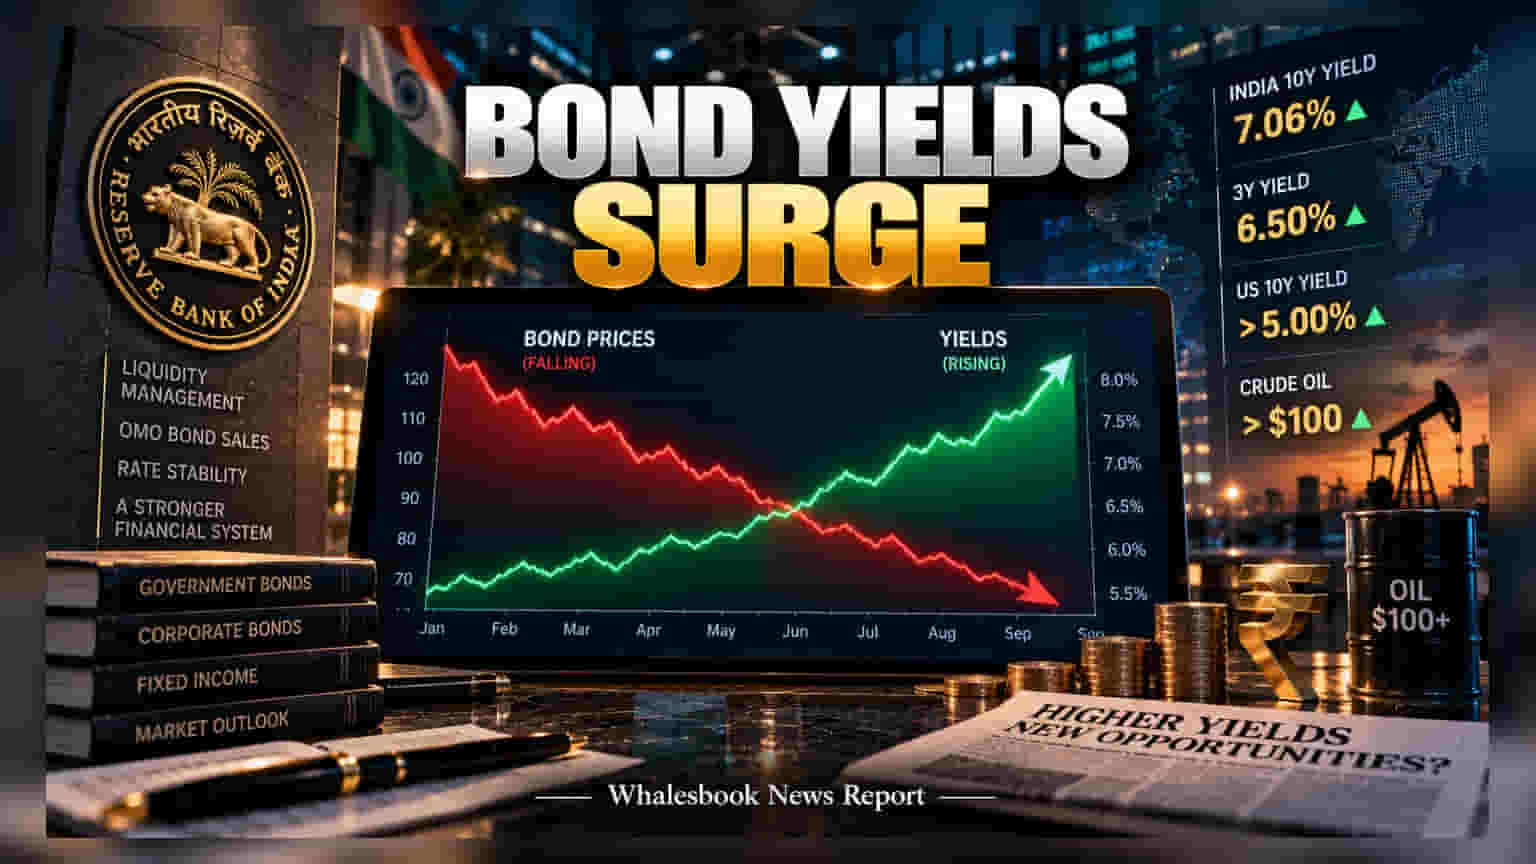
Indian bond yields have climbed as the Reserve Bank of India conducts bond sales to mop up excess liquidity. While this has led to recent volatility in fixed-income markets, the rise in yields and wider spreads are creating fresh opportunities for investors in short-term corporate bonds.
The Indian bond market has witnessed a notable change in sentiment as the Reserve Bank of India (RBI) manages a massive influx of liquidity. Following the FCNR(B) deposit scheme, which attracted $136 billion—significantly higher than the initial expectations of $50–$70 billion—the central bank has been active in absorbing excess cash from the banking system. To stabilize liquidity, the RBI has conducted Open Market Operation (OMO) bond sales worth Rs 750 billion, with an additional Rs 250 billion tranche scheduled for September 28. These actions, combined with efforts to manage currency volatility, have direct implications for market liquidity and interest rate movements.
Global Factors Pressuring Local Yields
The rise in domestic yields is not occurring in isolation. It is driven by a combination of global and local factors that have made the interest rate environment more challenging. Benchmark yields have adjusted upward, with 10-year government bond yields climbing to approximately 7.06%. At the same time, the 3-year government bond yield has moved from 6.2% in early August to 6.5%. The market is also reacting to global pressure, specifically crude oil prices breaching the $100 per barrel mark and the 10-year US Treasury yield crossing the 5% threshold. These external factors have forced the RBI to maintain a more cautious, or hawkish, stance on interest rates.
Valuation and Corporate Bond Spreads
For fixed-income investors, this environment of rising yields presents a complex trade-off. While the price of existing bonds often falls when yields rise, the current situation has created a valuation cushion in the corporate bond segment. Currently, 3-year AAA-rated corporate bonds are yielding nearly 7.7%. In the 1–3 year segment, investors are seeing spreads of approximately 250 basis points over the repo rate. This means that even if interest rates do not fall immediately, the higher starting yields and the carry—the return earned for holding the bond—can provide a more stable return structure for portfolios.
Risks and Future Monitorables
While the current spreads offer potential for disciplined investors, the market remains sensitive to inflationary pressures and future RBI policy decisions. The primary risk for investors in this environment is continued volatility if global interest rates, particularly in the US, remain elevated for longer than expected or if crude oil prices continue to put pressure on the domestic economy. Investors will be closely tracking the upcoming OMO sales on September 28 and any new communication from the RBI regarding its liquidity management strategy. The ability of the central bank to balance inflation control with support for growth will be the key factor determining the direction of bond yields in the coming quarters.