

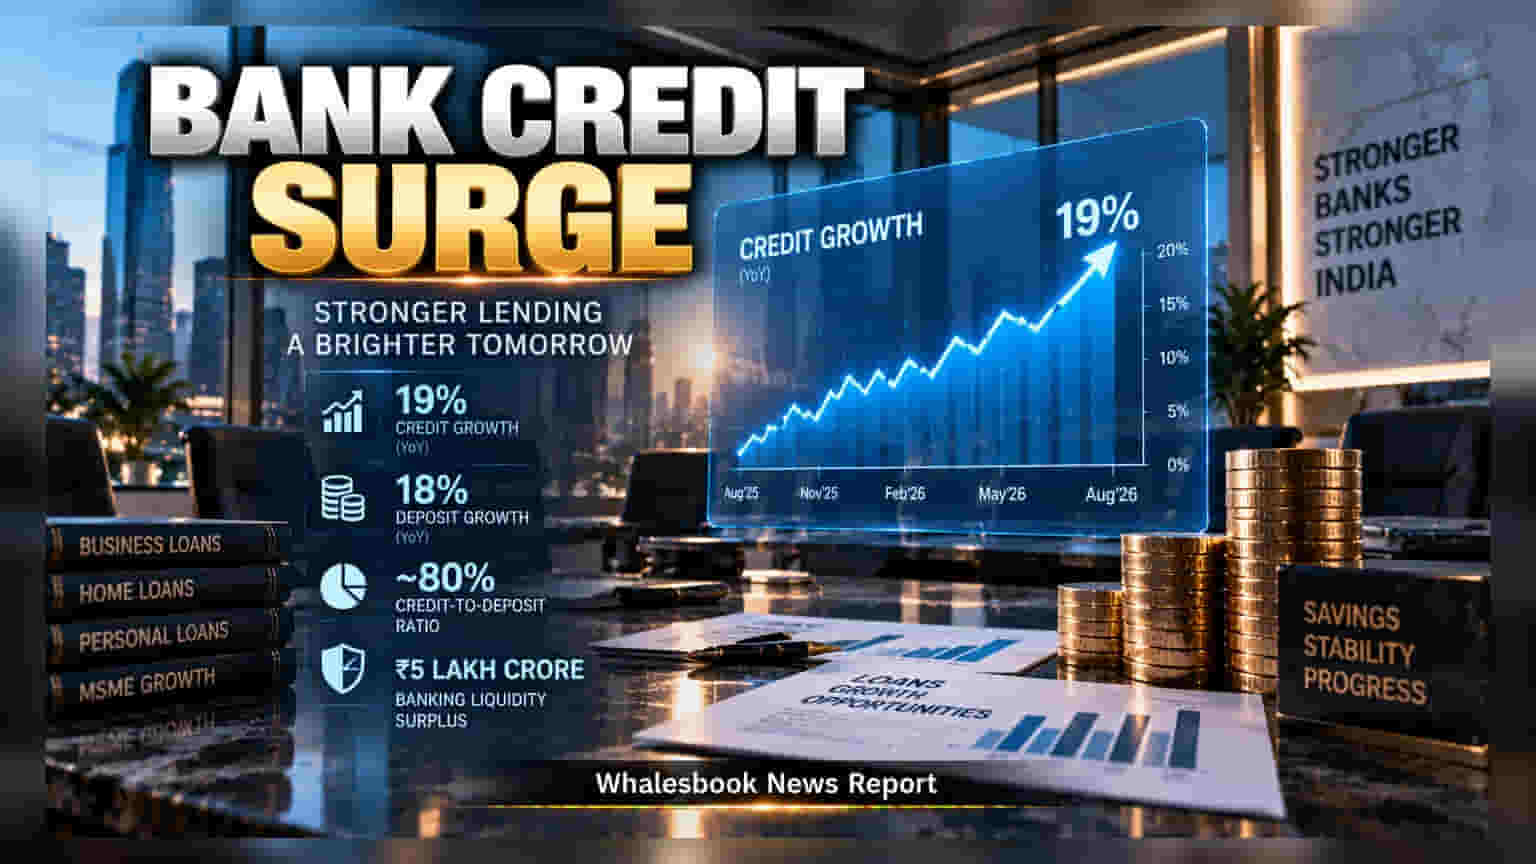
India's banking sector reported 19% credit growth and 18% deposit growth as of late August. This narrowing gap between loans and deposits indicates improved stability for lenders. Investors should watch if banks can sustain this balance, as strong lending often requires consistent deposit inflows to support profit margins.
Indian banks are showing strong lending activity with credit growth reaching 19 percent year-on-year as of August 31, 2026. This data highlights that businesses and individuals continue to seek loans at a steady pace. Alongside this, banks have managed to attract more money from savers, with deposit mobilization growing at 18 percent over the same period. This balanced growth helps banks manage their operations effectively without relying too heavily on more expensive sources of funding.
Banking Liquidity and Lending Ratios
A critical measure for any bank is the credit-to-deposit ratio, which tracks how much of a bank's total deposits have been lent out as loans. As of late August, this ratio is hovering near 80 percent, a level that shows banks are actively deploying their funds. At the same time, the banking system has maintained a liquidity surplus of approximately ₹5 lakh crore as of September 21. This surplus acts as a buffer, ensuring that banks have enough cash on hand to meet immediate demands while continuing to fund new loan applications.
What This Means for Bank Profitability
For investors, the relationship between loan growth and deposit growth is a key indicator of potential profit trends. When credit growth consistently outpaces deposit growth, banks often face pressure to increase the interest rates they offer to depositors to attract more funds. This can lead to higher costs for the bank and potentially squeeze their net interest margins, which is the difference between interest earned on loans and interest paid on deposits. By growing deposits at nearly the same rate as credit, banks are signaling a more stable path to funding their loan books.
Future Outlook and Monitorables
While the current expansion is robust, the banking sector faces potential shifts in global funding conditions and local economic changes that could influence future growth. Analysts suggest that the pace of credit expansion may see some moderation in the coming months. For investors, the primary factor to monitor will be whether banks can continue to attract sufficient deposits to sustain their lending targets. If deposit growth starts to lag significantly behind credit growth, banks might find it harder to maintain their current profit margins, which could impact their performance in the remaining quarters of the fiscal year.