

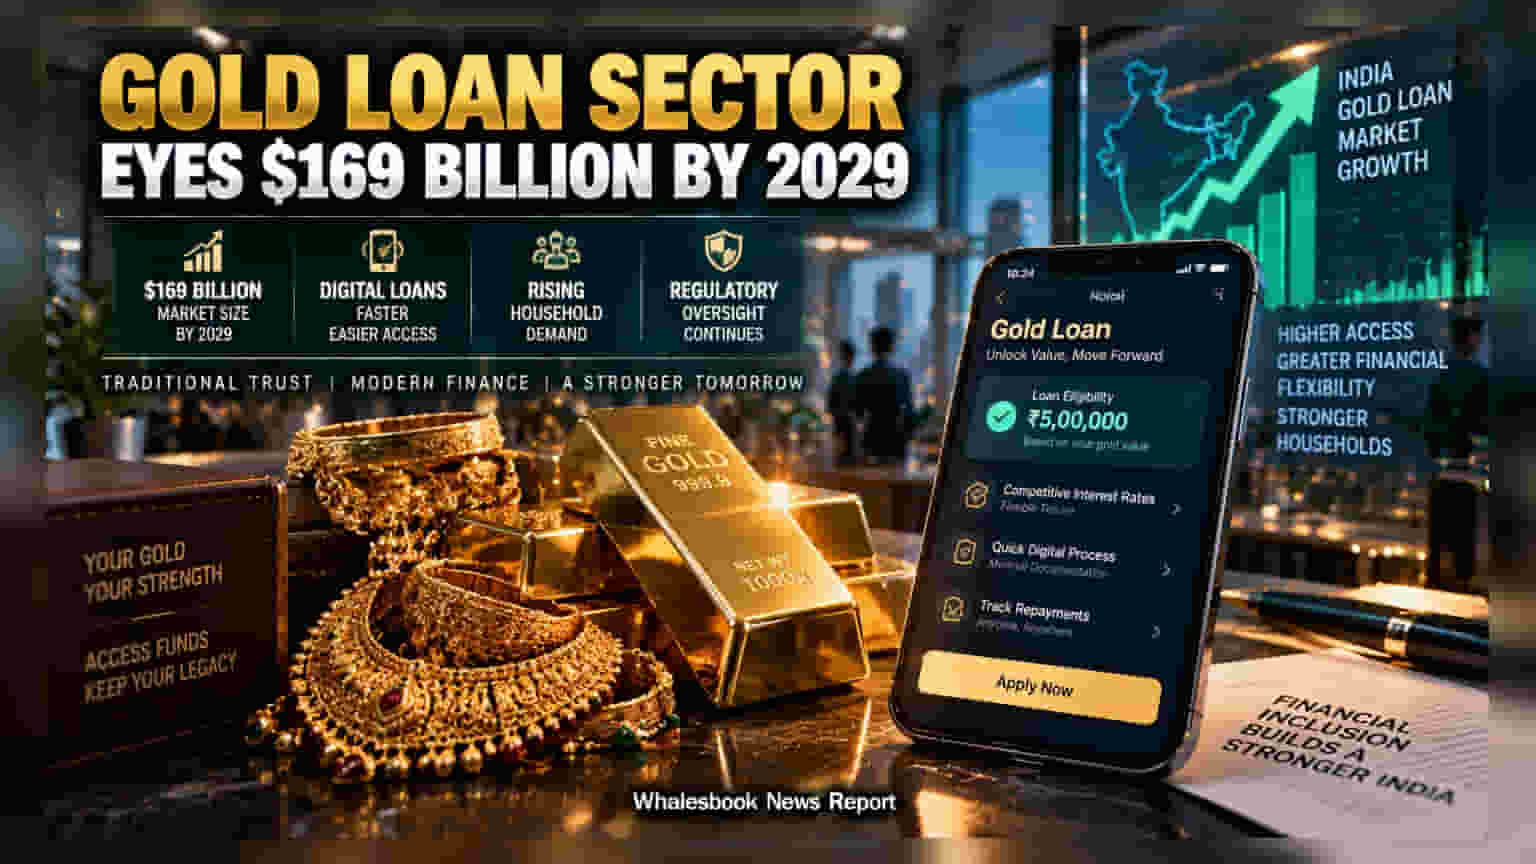
India’s gold-backed lending market is projected to reach $169 billion by 2029, as households prioritize quick cash without selling long-term assets. While digital convenience is fueling this expansion, investors should monitor the regulatory environment and how lenders manage collateral risks in a fluctuating gold price environment.
The gold loan sector in India is undergoing a significant expansion, with industry projections suggesting the market could grow to $169 billion by 2029. This trend highlights a fundamental change in how Indian households manage their finances during times of temporary cash shortage. Instead of selling off long-term investments like stocks or liquidating savings, families are increasingly using physical gold as collateral to secure loans. This approach allows them to keep their gold assets while meeting immediate capital needs.
Digital Transformation and Regulatory Watch
The adoption of digital technology has removed many traditional bottlenecks in the gold lending process. Borrowers can now use mobile applications to check their loan eligibility, compare interest rates, and track repayment schedules in real-time. This ease of access has helped non-banking financial companies (NBFCs) and banks broaden their reach, attracting customers who prefer convenience. However, this growth is subject to strict oversight. The Reserve Bank of India has historically issued guidelines to ensure that lending remains transparent and that valuation practices are robust.
For investors, companies like Muthoot Finance and Manappuram Finance remain central to this story. These established players have deep expertise in gold appraisal and secure storage, which acts as a business advantage. Yet, the sector faces specific risks. Since the loan amount depends on the market price of gold, any sharp decline in gold prices can force lenders to issue margin calls or, in extreme cases, auction the collateral. Investors should watch how these companies manage their loan-to-value ratios to protect against such volatility.
Furthermore, the competitive landscape is intensifying as traditional banks aggressively push into the gold loan space. The next key monitorable for shareholders will be how these gold-focused lenders maintain their profit margins while competing on interest rates. Additionally, keeping an eye on quarterly updates regarding bad loan levels and any new regulatory announcements will be crucial, as these factors directly impact the long-term sustainability of the sector.