

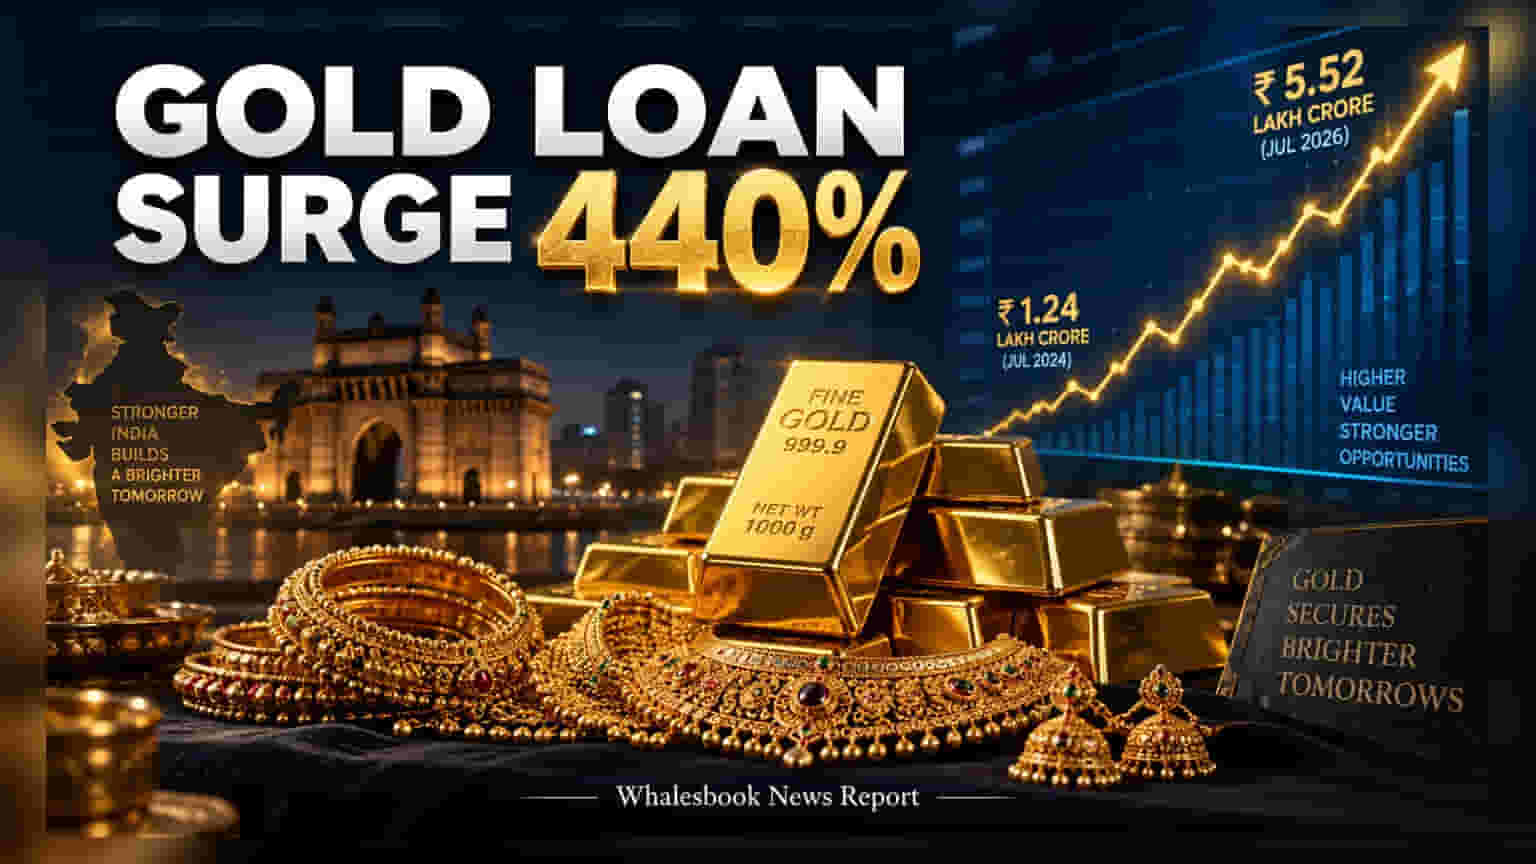
India’s gold loan market has surged 4.4 times to ₹5.52 lakh crore by July 2026, as banks shift away from high-risk unsecured credit. This pivot to gold-backed lending is driven by rising gold prices and favorable regulatory norms, making these loans a key part of household finance. Investors should track how this rapid growth affects bank balance sheets and asset quality if gold prices fluctuate.
The Indian gold loan market has seen a rapid transformation, with outstanding loans against gold jewellery reaching ₹5.52 lakh crore by July 2026. This represents a 4.4-fold increase in just two years, compared to ₹1.24 lakh crore in July 2024. As a result, gold loans now account for 7.7 percent of India's personal credit pool, a significant jump from 2.2 percent two years ago.
This growth marks a clear shift in how Indian banks are managing their loan books. In recent times, many lenders have become cautious about aggressive expansion in unsecured lending, such as credit cards and personal loans, due to concerns over high default rates and regulatory tightening. Gold loans, being secured by physical assets, provide banks with a lower-risk alternative. Because the loan is backed by gold, recovery is easier for lenders if a borrower cannot repay, making it a preferred product during times of economic caution.
Regulatory Support and Gold Prices
Two major factors have acted as tailwinds for this growth. First, regulatory norms have become more favorable for smaller borrowers. The Reserve Bank of India’s current rules allow lenders to offer financing of up to 85 percent of the gold’s value for smaller loans of up to ₹2.5 lakh. This has made borrowing against gold more accessible than traditional credit products.
Second, the rise in gold prices has directly increased the borrowing capacity of households. With gold trading near ₹1.52 lakh per 10 grams, the same amount of jewellery provides higher collateral value, allowing for larger loan amounts. Banks, including public sector lenders like Punjab National Bank, have cited clear guidelines as a reason for their increased activity in this segment.
Regional Spread and Potential Risks
While South India—particularly Tamil Nadu, Andhra Pradesh, and Karnataka—remains the largest market, contributing over 70 percent of total gold-backed loans, the geography is shifting. Faster growth rates are now visible in northern and eastern states, including Uttar Pradesh and West Bengal. This shows that gold loans are becoming a standard financing option across the country, not just in the southern states where it has historically been popular.
However, this rapid expansion brings specific business risks that investors should understand. The primary risk is linked to the price of gold itself. If gold prices drop sharply, the loan-to-value ratio changes, which may require banks to ask borrowers for extra collateral or top-up payments. Additionally, the gold loan sector is highly competitive. Non-banking financial companies (NBFCs) like Muthoot Finance and Manappuram Finance have traditionally dominated this space, and they now face increased competition from commercial banks that are aggressively targeting the same customer base.
For investors, the key monitorables are asset quality metrics and profit margins. While delinquency rates for gold loans are currently low, maintaining this quality will be critical as banks expand into new regions. Investors should also watch for any changes in the competitive landscape, as aggressive pricing by banks to capture market share could put pressure on the interest margins of specialized gold lenders.