

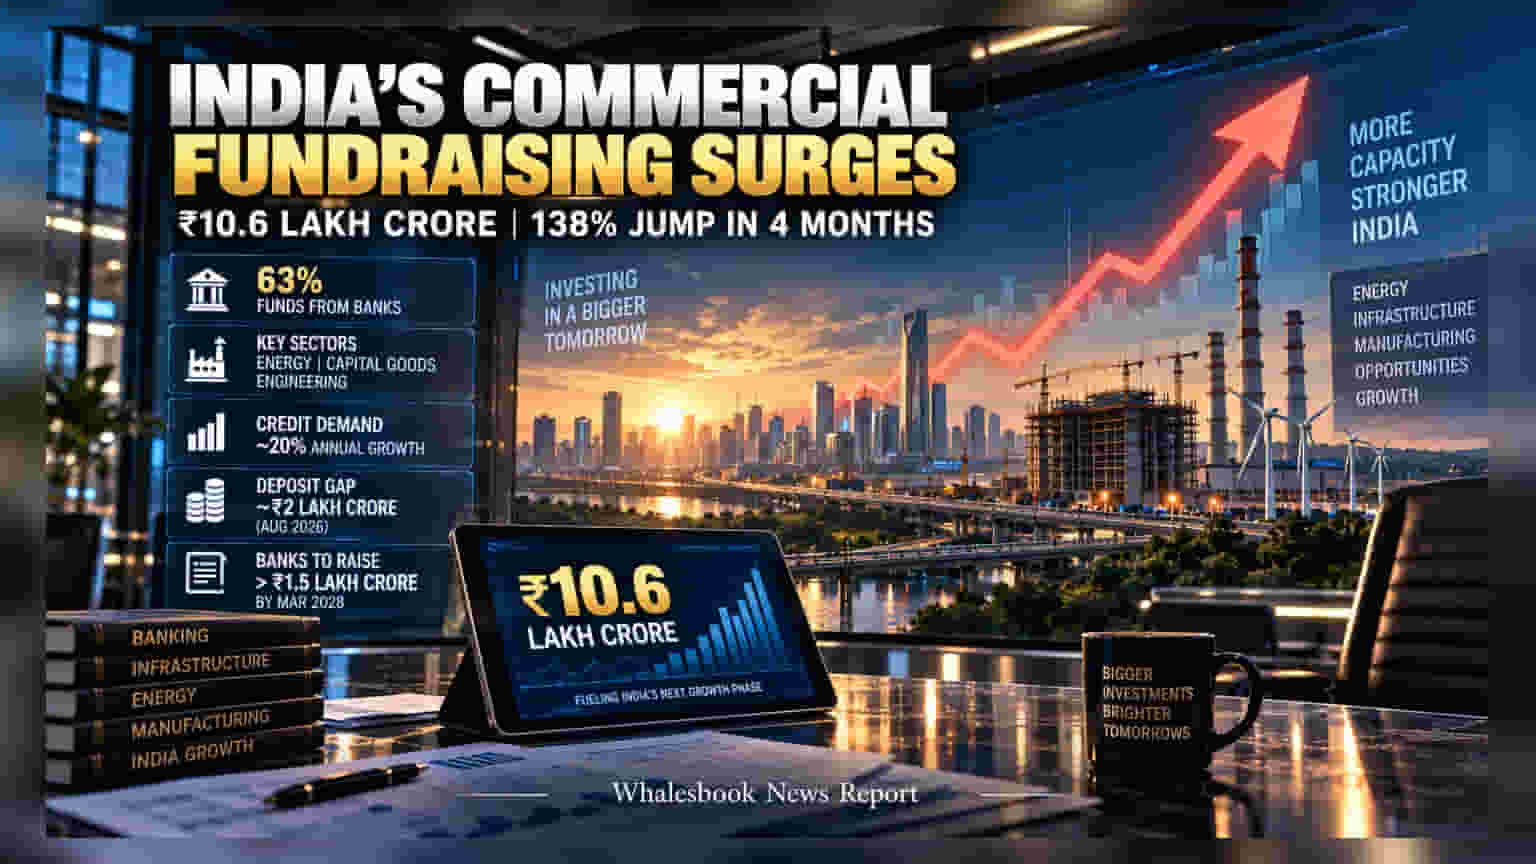
Corporate fundraising jumped 138% to ₹10.6 lakh crore in the first four months of FY27, as Indian banks took charge of financing business expansion. This surge highlights a recovery in capital spending, particularly in energy and engineering sectors, though it also signals upcoming capital requirements for lenders as they manage debt refinancing.
In the first four months of the current financial year, India saw a massive 138% rise in commercial fundraising, reaching ₹10.6 lakh crore. Banks have become the primary source for this money, providing about 63% of the total funds. This shift indicates that companies are increasingly relying on traditional bank loans to fund their operations rather than raising money through capital markets.
Impact on Capex and Key Sectors
The surge in borrowing is largely flowing into sectors like energy, capital goods, and engineering. This indicates that private companies are spending heavily on building new capacity and infrastructure. The credit demand in the industry is growing at nearly 20% annually, which suggests businesses are confident about long-term demand and are actively expanding their operational footprint. This private spending cycle is a critical indicator of economic health, as it often leads to job creation and improved manufacturing output.
Banking Liquidity and Deposit Trends
For banks, the immediate liquidity pressure has eased slightly. A major gap in deposits, which was a constraint earlier, has reduced to roughly ₹2 lakh crore as of August 2026. This was helped by strong inflows into FCNR(B) deposits, which are foreign currency accounts held by non-resident Indians. Currently, the credit-deposit ratio—a measure of how much of the deposited money is lent out—sits at 80.6%. While this shows healthy and active lending, it also means banks are using a large portion of their available cash for loans, leaving less room for aggressive lending without bringing in new deposits.
Future Capital Requirements
Looking ahead, this aggressive lending cycle brings new challenges for the banking sector. Banks will likely need to raise over ₹1.5 lakh crore in fresh capital by March 2028. A significant reason for this is the need to refinance Basel III Additional Tier 1 (AT1) bonds. These are specialized debt instruments that banks issued in the past to maintain capital buffers. Public sector banks, which hold a large portion of these bonds approaching their call dates, will be under the most pressure to raise funds to replace or repay this debt. For shareholders, this future requirement could potentially lead to equity dilution or the issuance of new debt, which may impact bank stock performance in the long run.
Investors should keep a close watch on future bank earnings and official announcements regarding capital raising plans. Additionally, the pace of actual capital spending on the ground in the energy and engineering sectors remains a key metric to judge the sustainability of this credit growth.