

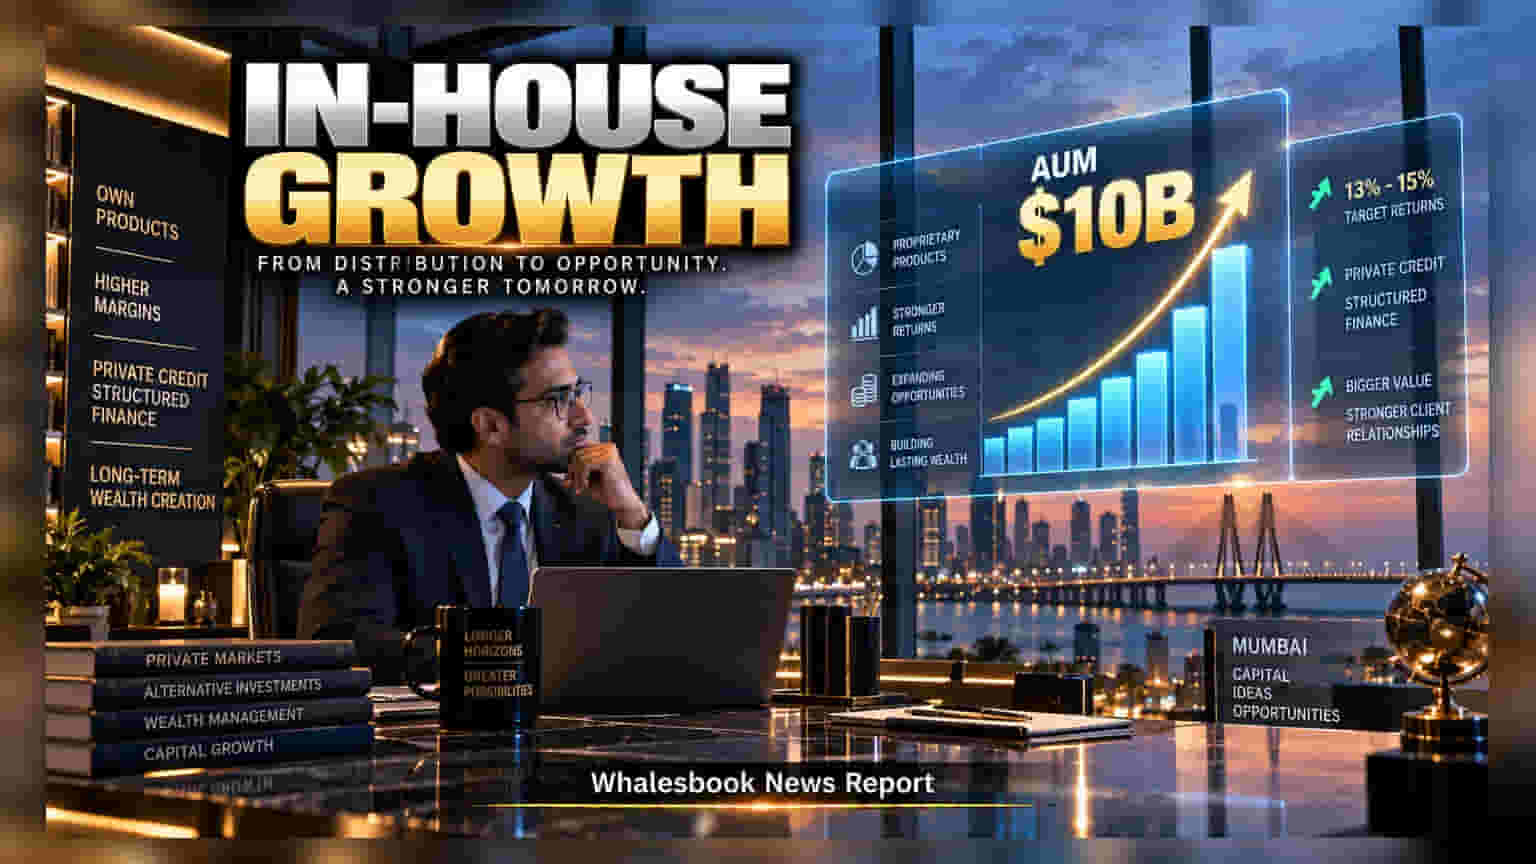
InCred Wealth has reached $10 billion in assets under management and is now pivoting to create its own investment products instead of distributing third-party funds. This strategy aims to improve margins by focusing on private credit and structured assets. While the move helps the firm compete with larger rivals, it also changes the risk profile by moving from a simple sales model to managing complex financial products.
InCred Wealth is changing its business strategy as it hits a milestone of $10 billion in assets under management. The firm, led by CEO Nitin Rao, is moving away from the traditional model of selling third-party investment products to focus on manufacturing its own proprietary offerings. This shift is a direct response to the increasing pressure on margins in the wealth management sector, where simple distribution services are becoming common and less profitable.
Moving From Distribution to Manufacturing
For years, many wealth managers earned revenue mainly through commissions by distributing funds and products created by others. However, InCred Wealth argues that this model is losing its edge. By creating its own investment products—specifically in private credit and structured finance—the firm aims to capture a larger share of the value. In the world of finance, manufacturing products typically allows a firm to keep a larger portion of fees, whereas distribution relies on sharing those fees with the actual product creators. Under this new strategy, the firm is prioritizing high-yield assets that can offer returns between 13% and 15% to its clients, largely sourced through the startup and private credit ecosystem.
Operational and Execution Risks
While the shift to in-house manufacturing can lead to higher margins, it also introduces different types of risks for the firm. Unlike a distributor, who is primarily responsible for selling products, a manufacturer takes on the responsibility for the underlying assets. If a private credit or structured product fails to perform or faces defaults, the wealth manager’s reputation is directly at stake. This creates a higher burden for the firm’s credit assessment and risk management teams.
Furthermore, the regulator in India, the Securities and Exchange Board of India (SEBI), has been closely monitoring the Alternative Investment Fund (AIF) and private credit space. Increased regulatory scrutiny on how these products are structured, how liquidity is managed, and how risks are disclosed is a factor that investors and the firm must navigate. The firm will need to balance its pursuit of high-yield products with strict adherence to evolving compliance standards.
Competitive Landscape
InCred Wealth is operating in a competitive environment against established incumbents like 360 ONE and Nuvama. These larger firms have already built extensive in-house product platforms and long-standing relationships with ultra-high-net-worth individuals. For InCred, the success of this strategy will depend on whether its human advisory team can effectively guide clients through these new, proprietary products, ensuring that the shift to in-house manufacturing translates into long-term client retention rather than just a short-term product push. The next key monitorable will be the consistency of returns in these new private credit products and how the firm manages potential liquidity issues during market stress.