

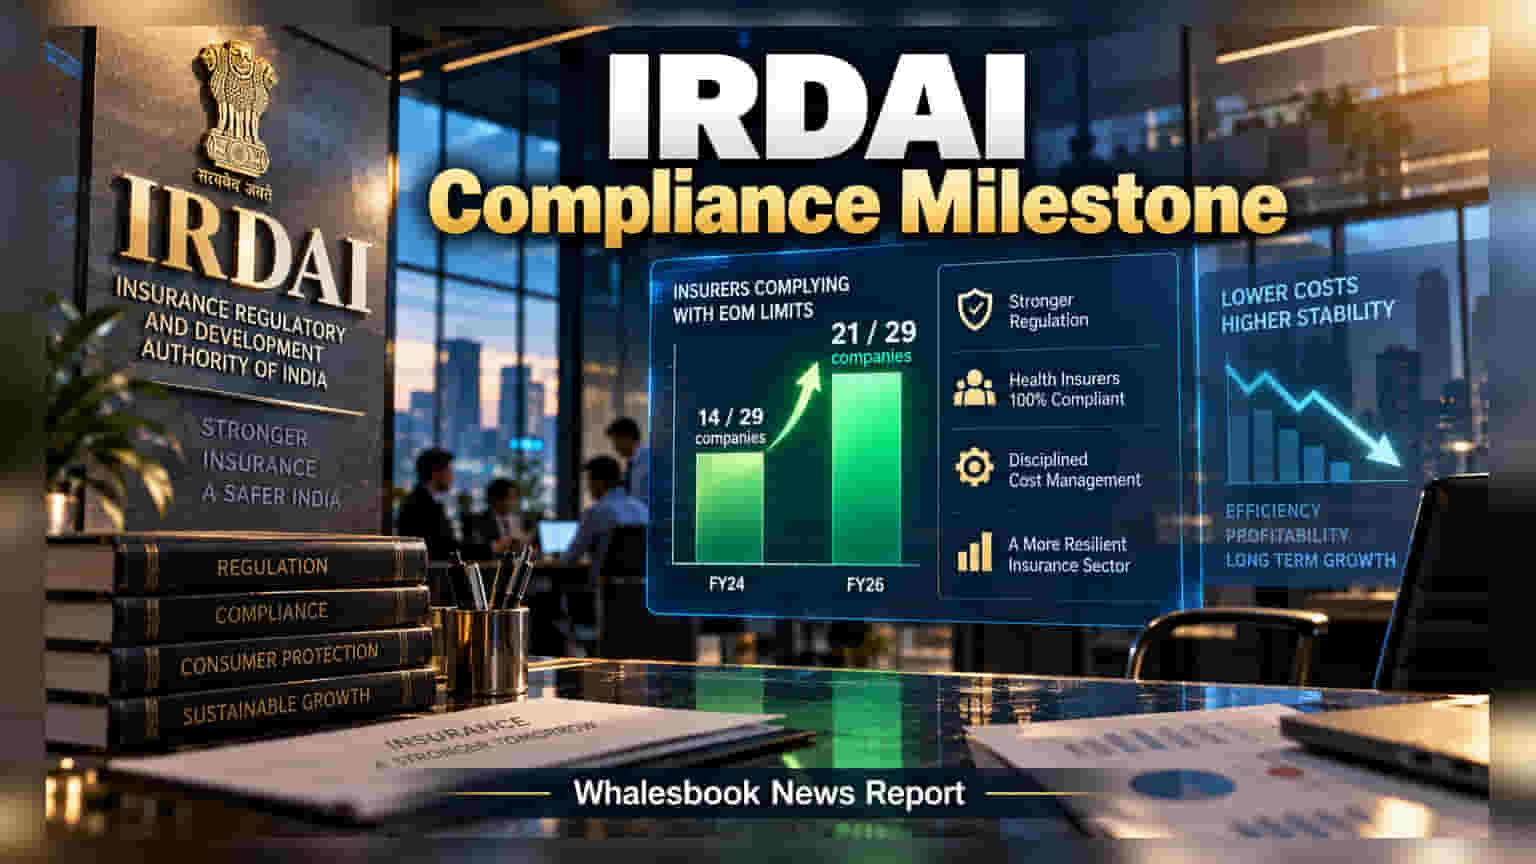
Twenty-one out of 29 insurance companies now meet the regulator's Expenses of Management (EOM) limits, a rise from 14 in FY24. This push by the IRDAI aims to curb excessive spending and improve sector efficiency. Investors may note that general insurers remain slightly above the 30% threshold, while standalone health insurers have achieved full compliance.
The insurance sector is seeing a shift toward stricter cost management under the guidance of the Insurance Regulatory and Development Authority of India (IRDAI). As of FY26, 21 out of 29 tracked insurance companies now operate within the mandated Expenses of Management (EOM) limits. This is a clear improvement from FY24, when only 14 firms met these requirements. The EOM limit is essentially a cap on how much a company can spend on administration, marketing, and commissions relative to the premiums they collect.
The regulatory environment has become much tougher following the introduction of the Sabka Bima Sabki Raksha Act, 2025. This law gave the IRDAI stronger powers to monitor and control how much insurance companies pay in commissions and how much they spend on operational costs. The regulator's goal is to ensure companies remain financially healthy and do not overspend to acquire business.
Standalone health insurance companies have shown strong discipline, with every tracked firm now operating within the required limits. This is a significant turnaround from two years ago when only one player was compliant. The general insurance segment, however, is facing more complexity. While 14 out of 20 tracked general insurance entities are compliant, the sector’s weighted average EOM ratio stands at 30.4%, which is slightly above the 30% ceiling set by the regulator.
Major market players, such as ICICI Lombard, Bajaj General, Tata AIG, and HDFC Ergo, have maintained compliance, although their combined weighted EOM ratio has drifted up to 29.7% over the last three years. The IRDAI has shown it is serious about enforcement. Recently, four companies that failed to meet the norms faced a six-month ban on opening new business locations.
Some smaller insurers, including Acko, Navi General, and Zuno, have taken steps to reduce their EOM ratios to bring their cost structures in line with the new rules. The insurance industry is currently waiting for a revised commission structure, which is being consulted on by the regulator. Because the IRDAI is actively looking at these spending habits, insurers must balance their growth targets with the need to keep costs within the allowed limits. The key monitorable for investors will be how these spending restrictions affect profit margins and whether the regulator announces further policy changes regarding commission payouts.