

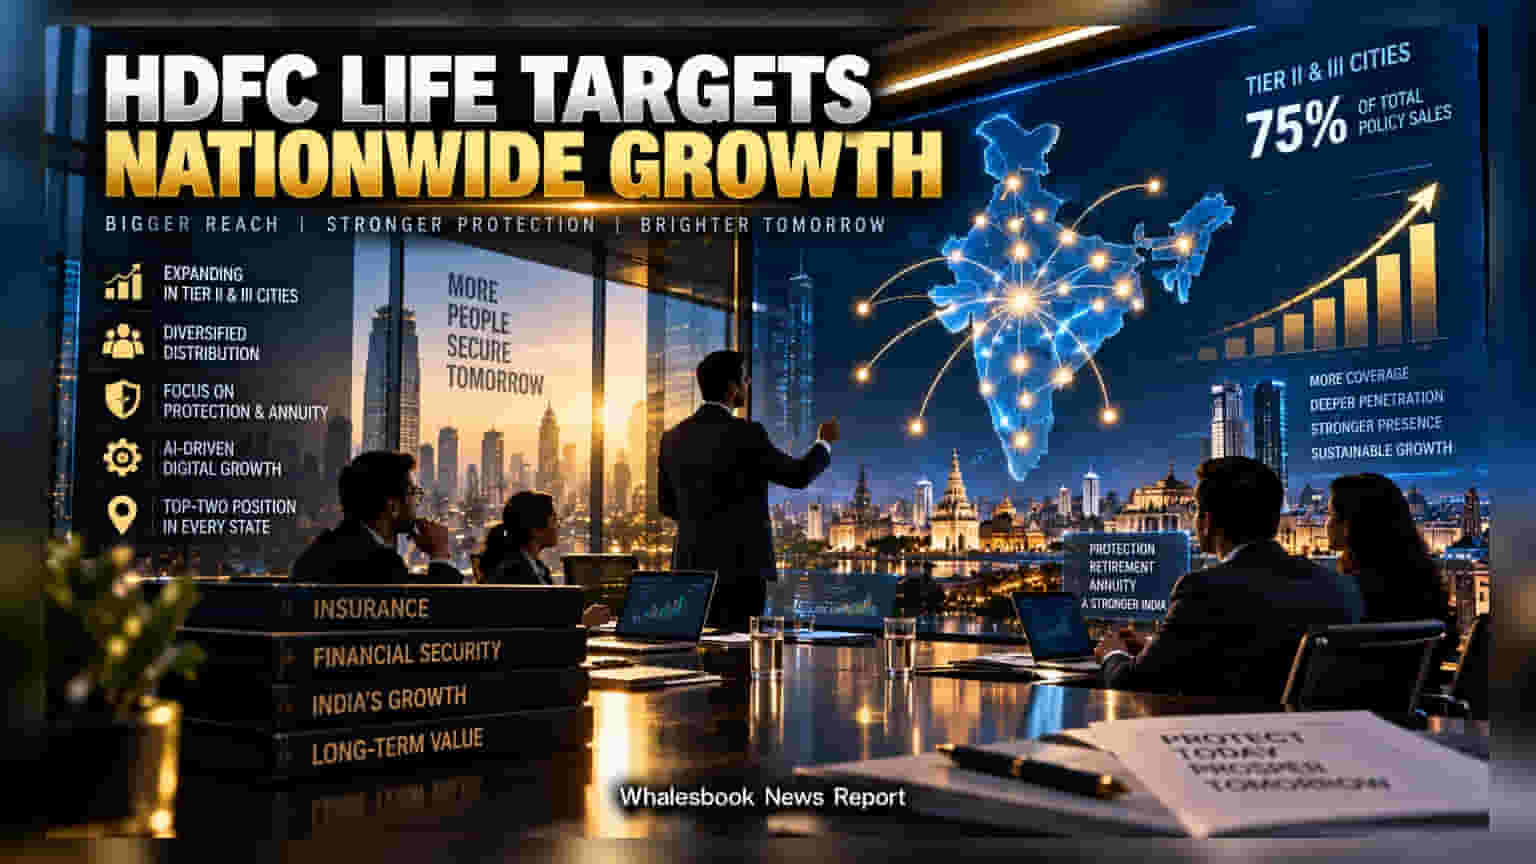
HDFC Life Insurance is aiming for a top-two market position in every Indian state by expanding into Tier II and III cities. The company is actively reducing its reliance on HDFC Bank, which now accounts for 47% of retail sales, as it shifts focus toward a more diversified distribution network and higher-margin protection products.
HDFC Life Insurance has outlined a strategy to secure a top-two market share position in every state across India. The insurer is focusing on regional growth by increasing its presence in Tier II and III cities, which currently account for 75% of its total policy sales. This shift is a key part of the company's plan to reduce dependence on its primary bancassurance partner, HDFC Bank, where retail sales contribution has decreased from 51% in recent years to approximately 47%.
The Shift from Bancassurance
For years, private life insurers in India have relied heavily on bancassurance, which is the selling of insurance products through bank branches. While this channel offers lower customer acquisition costs compared to agency networks, it creates concentration risk. By actively diversifying into agency, direct, and other corporate channels, HDFC Life is attempting to mitigate this risk. Currently, bancassurance accounts for 55% of the company's retail annual premium equivalent, while the remaining 45% is driven by direct, brokerage, and agency forces. Investors should note that while this diversification improves stability, building agency forces and direct sales often leads to higher operating expenses compared to selling through existing bank branches.
Growth Engine in Smaller Cities
Expansion into smaller cities has become the primary growth driver for the insurance sector. HDFC Life is aiming to increase its penetration in these regions by 100 to 150 basis points each year. This is being supported by a shift in consumer demand toward protection, retirement, and annuity products. Unlike pure market-linked plans, these categories provide more predictable long-term outcomes, which aligns with the current consumer preference for stability amidst market volatility.
Competitive Landscape
The Indian life insurance sector remains highly competitive, with players like SBI Life Insurance and ICICI Prudential Life Insurance vying for market share. SBI Life, in particular, leverages the massive network of the State Bank of India, which presents a structural advantage in terms of captive distribution reach. HDFC Life's attempt to achieve a top-two rank in every state is a direct effort to replicate this reach without being overly dependent on a single parent institution. Furthermore, the company is integrating AI-driven digital platforms to engage younger demographics, a move aimed at lowering the cost of servicing these customers in newer geographies.
What Investors Should Track
The long-term impact of this strategy will depend on the company's ability to manage costs while expanding geographically. Investors may monitor the trend in operating expenses and the sustainability of profit margins as the distribution mix shifts away from the bank channel. Additionally, upcoming quarterly results will likely highlight whether the increased focus on Tier II and III cities is translating into profitable growth and whether the change in product mix toward annuity and protection plans is supporting overall margins.