

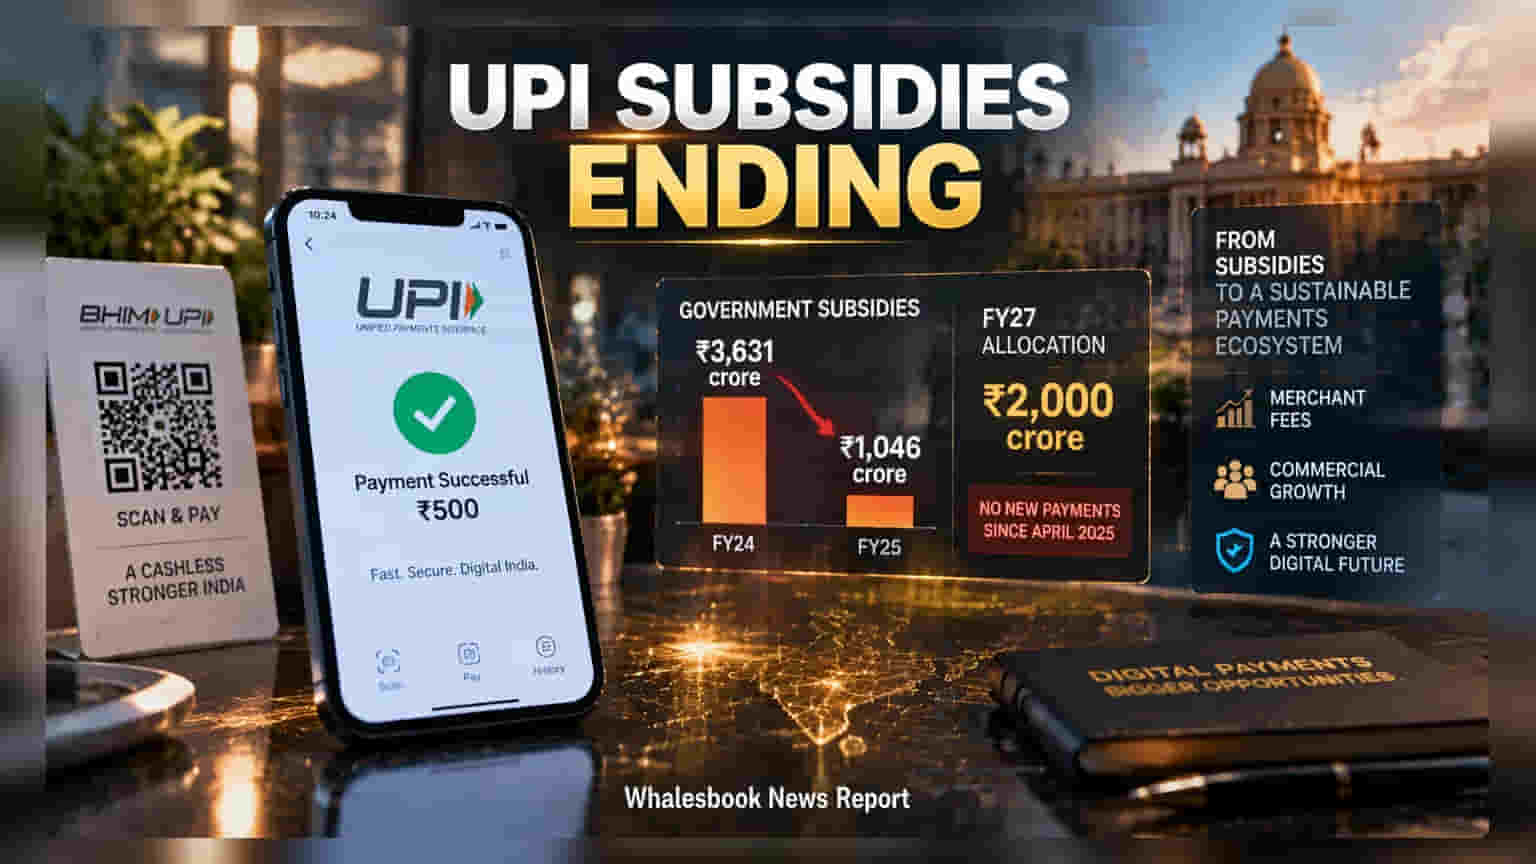
India is moving away from taxpayer-funded incentives for UPI transactions, pushing the digital payment ecosystem toward self-sustainability. With subsidy payouts dropping significantly since fiscal year 2024, banks and payment providers are now increasingly relying on transaction fees paid by merchants. This policy transition shifts the sector from a government-subsidized growth phase to a market-driven revenue model.
The Indian government is transitioning away from providing direct subsidies for UPI and RuPay transactions, moving the digital payments sector toward a model where companies generate revenue from processing fees. This marks a significant shift from the strategy that fueled the early, rapid adoption of digital payments, where the government compensated banks and payment providers to cover infrastructure costs during the rollout phase.
Official data reveals a clear retreat from these incentives. Total government spending on UPI and RuPay subsidies fell to ₹1,046 crore in FY25, down from ₹3,631 crore in FY24. While the government has allocated ₹2,000 crore for such incentives in the FY27 budget, no new payments have been processed for transactions since April 2025. This indicates that the government now views the digital payment infrastructure as sufficiently mature to function without continuous financial support from the public exchequer.
For investors, this policy change fundamentally alters how banks and payment platforms generate income. Previously, the government ensured that platforms did not incur losses on transaction volumes by offering compensation. Under the new approach, companies must rely on the Merchant Discount Rate (MDR) or other service fees charged to larger merchants to cover costs and generate profit. This places the responsibility of monetization on the private sector, moving the industry from a subsidized utility model to a commercial revenue model.
This transition comes with specific operational challenges. The key risk is whether merchants are willing to pay these transaction fees without reducing their usage of digital payment platforms. If these fees become too high, it might discourage small merchants from accepting digital payments, potentially slowing down the transaction growth rates that the market is accustomed to.
Investors monitoring the sector should track how payment service providers manage this shift. The critical factor will be whether companies can implement fee structures that cover costs without compromising the massive reach and volume of the UPI network. Moving forward, quarterly financial reports from banks and fintech companies will provide clarity on how much revenue is being generated from these merchant transaction fees compared to the previous, government-backed subsidy model.