

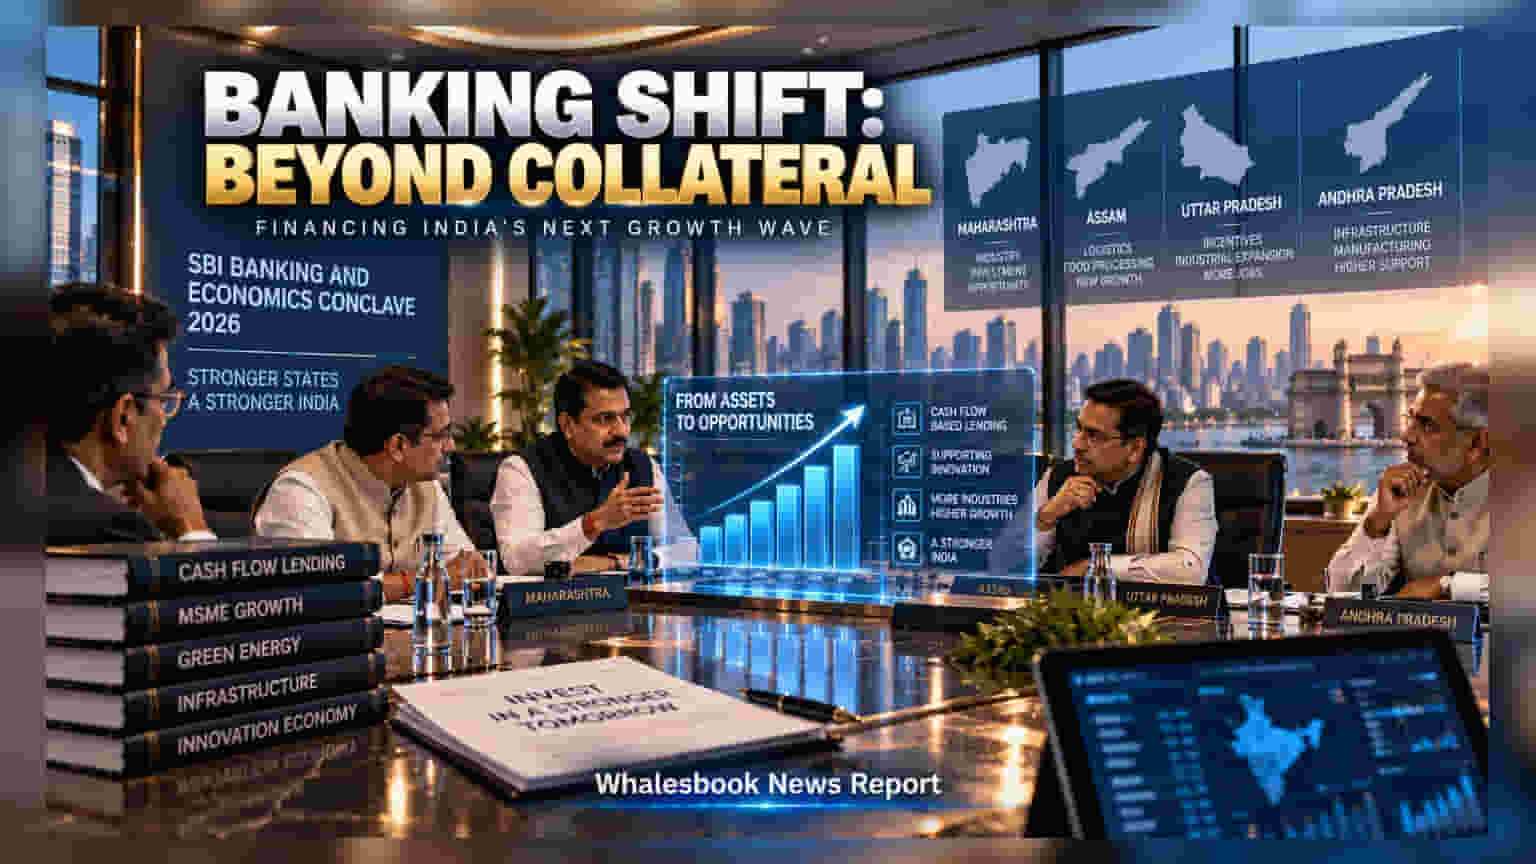
State finance ministers are urging Indian banks to reduce reliance on collateral-heavy loans, favoring models based on future cash flows. This shift aims to support emerging industries like green energy and technology, which often lack large physical assets. For investors, this marks a potential change in how banks evaluate credit risk and could influence future asset quality and loan growth strategies for the banking sector.
At the SBI Banking and Economics Conclave 2026, finance ministers from Maharashtra, Assam, Uttar Pradesh, and Andhra Pradesh advocated for a significant change in how Indian banks provide credit. The current lending system in India is largely focused on physical collateral—assets like land, buildings, or machinery that a borrower pledges to secure a loan. The ministers argued that this traditional approach is becoming a barrier to growth for modern, service-oriented, and technology-driven industries.
Why the Shift Matters for Growth
Modern businesses, particularly in green energy, advanced manufacturing, and logistics, often have high potential for future earnings but may not have large physical properties to pledge as security. By moving to cash-flow based lending, banks would evaluate a company's ability to generate steady income and profit, rather than just the value of the assets it owns. This approach is common in more developed economies and is designed to unlock capital for startups and ancillary sectors that are currently underserved by traditional financing.
Regional Industrial Efforts
States are already taking steps to encourage private investment, which creates a natural demand for more flexible credit. For instance, Assam is focusing on logistics and food processing, recently seeing significant private investment such as the ₹778 crore PepsiCo plant. Uttar Pradesh has been aggressive with its incentive-linked policies, reporting the disbursement of nearly ₹17,000 crore in incentives during the current fiscal year to boost industrial activity. Meanwhile, Andhra Pradesh is seeking higher support from the federal government, arguing that economic success should be measured by the commercial activity generated on the ground.
Potential Risks and Investor Monitorables
While this shift could boost industrial growth, it introduces new challenges for the banking sector. Loans secured by physical collateral are generally safer because the bank has a tangible asset to sell if the borrower fails to pay. Cash-flow lending requires banks to be far more skilled at assessing a business model, predicting future demand, and monitoring ongoing performance. If banks adopt this model without robust risk-management systems, there is a risk that loan defaults could rise during economic downturns.
For investors, the key monitorable will be how banks balance this new lending strategy with their need to protect profit margins and asset quality. It is important to watch how large public and private sector banks adjust their credit assessment frameworks over the coming quarters. Investors should monitor quarterly reports for any changes in the mix of collateralized versus non-collateralized loans, as well as any trends in bad loans from sectors that rely heavily on these new, flexible financing arrangements.