

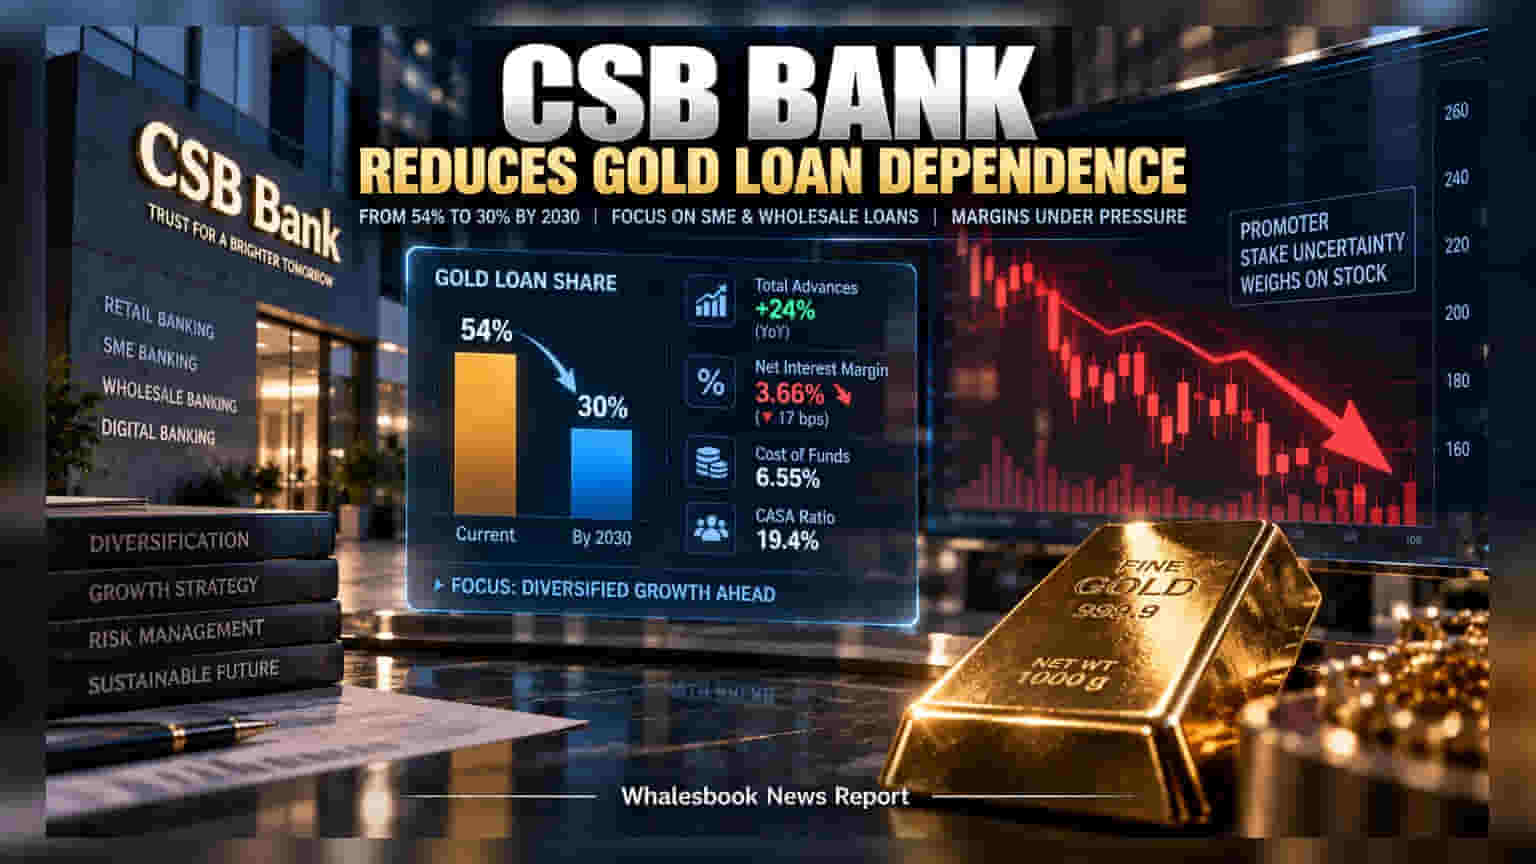
CSB Bank is shifting its strategy to reduce gold loan dependency to 30% by 2030, though high deposit costs are currently squeezing profit margins. Investors are tracking how the lender improves its low-cost deposit mix and the potential impact of a possible exit by promoter Fairfax.
CSB Bank is currently undergoing a significant strategic transition as it looks to reduce its heavy dependence on gold loans. The bank, which has historically relied on gold-backed lending for a large portion of its business, is now aiming to pivot toward a more diversified model. By 2030, the management plans to bring down the share of gold loans in its total advances to 30 percent from the current level of approximately 54 percent. While the bank reported a 24 percent growth in total advances compared to the same period last year, this transition to wholesale and small business (SME) loans remains a complex task that could take several years to show full results.
Challenges in Margins and Deposits
A primary hurdle for the bank is the pressure on its profit margins. The net interest margin—which shows the difference between the interest earned on loans and the interest paid on deposits—declined to 3.66 percent in the recent quarter, a drop of 17 basis points. This decline is largely due to the bank's reliance on high-cost bulk deposits, which currently make up 42 percent of its total deposit base. At the same time, the ratio of low-cost money held in current and savings accounts (CASA) has fallen to 19.4 percent. This situation has driven the bank's cost of funds up to 6.55 percent. While management has indicated that they expect some recovery in margins starting in the second quarter, analysts are focusing on whether the bank can successfully improve its deposit mix, which is viewed as a long-term goal.
The Promoter Stake Uncertainty
Beyond operational metrics, the stock is also influenced by uncertainty regarding its promoter, Fairfax. Speculation about a potential stake sale by the promoter has created a cloud of uncertainty. Such situations often create a 'technical overhang,' where the fear of potential selling pressure from a major shareholder can limit the stock price, even if the underlying business appears reasonably valued. This factor remains an important consideration for investors monitoring the bank's near-term price movement.
Asset Quality Remains Stable
Despite the pressure on margins, the bank’s asset quality remains a bright spot. The lender has managed to keep its exposure to risky, unsecured loans to a low level of about 2 percent of its total portfolio. Furthermore, the overall rate of bad loans, or slippages, remains below 1 percent. With a provision coverage ratio of 78 percent, the bank appears to have built a sufficient financial cushion to handle moderate stress in the near term.
For investors, the most critical indicators to watch moving forward will be the quarterly progress in growing low-cost deposits (CASA) and signs of stability in fee income. The bank's ability to execute its shift toward SME and wholesale loans while managing the cost of its funds will define its growth path over the next few years.