

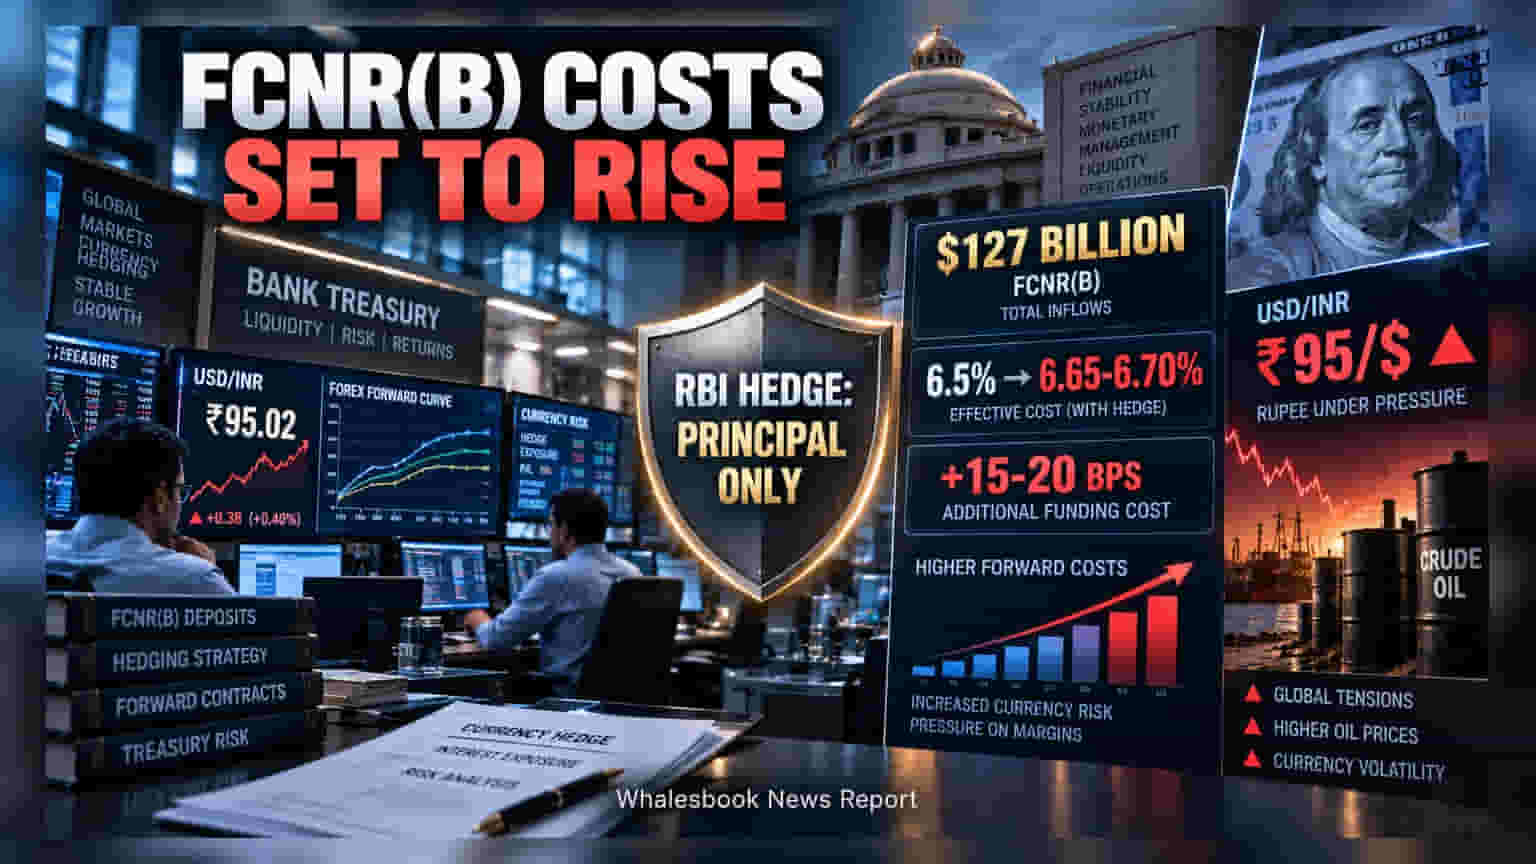
Indian banks are seeing an additional 15-20 basis point cost on FCNR(B) deposits because the RBI’s swap facility covers only the principal, not the interest. With $127 billion raised, this unhedged interest liability creates treasury pressure. As the rupee faces volatility, managing these currency risks may impact future profit margins for banks that heavily utilized the scheme.
Indian banks are currently adjusting to an unexpected layer of expense following the closure of the Foreign Currency Non-Resident (FCNR(B)) deposit window on August 31. While the scheme successfully attracted $127 billion into the banking system, it came with a specific condition: the Reserve Bank of India provided a swap facility to hedge the principal amount, but it did not cover the interest payments owed to depositors.
Because the interest liability remains in foreign currency, banks are now responsible for managing the currency risk associated with these future payouts. Banking experts estimate that this creates an additional funding cost of roughly 15 to 20 basis points. For instance, if a bank pays a 6.5% interest rate on a deposit, the actual cost of securing that money, after accounting for the hedge, rises to approximately 6.65% or 6.70%.
This gap is becoming more relevant as the Indian rupee faces pressure against the dollar. With the currency recently trading past the ₹95 mark amid global tension, the cost of forward contracts—which banks use to hedge this currency risk—has risen. If a bank chooses not to hedge the interest portion entirely, it exposes its balance sheet to the risk that a weaker rupee will make future interest payments much more expensive in rupee terms. Consequently, treasury teams are having to make difficult choices between paying higher current hedging costs or accepting higher future currency risk.
Beyond the interest cost, the massive inflow of $127 billion has created a liquidity surplus, complicating how the central bank manages money in the system. To prevent excessive liquidity from distorting rates, the Reserve Bank of India has actively stepped in. This includes conducting open market operations, such as bond sales, to sterilize the excess cash circulating in the market. This dual challenge—managing both the cost of these deposits and the liquidity they created—is keeping bank treasury desks busy.
For investors, the key takeaway is the potential impact on net interest margins. Banks that heavily relied on these deposits will need to carefully manage their hedging strategies to protect profitability. Moving forward, shareholders may watch for updates in quarterly results regarding treasury performance and how banks choose to balance their currency risk against the rising cost of hedging.