

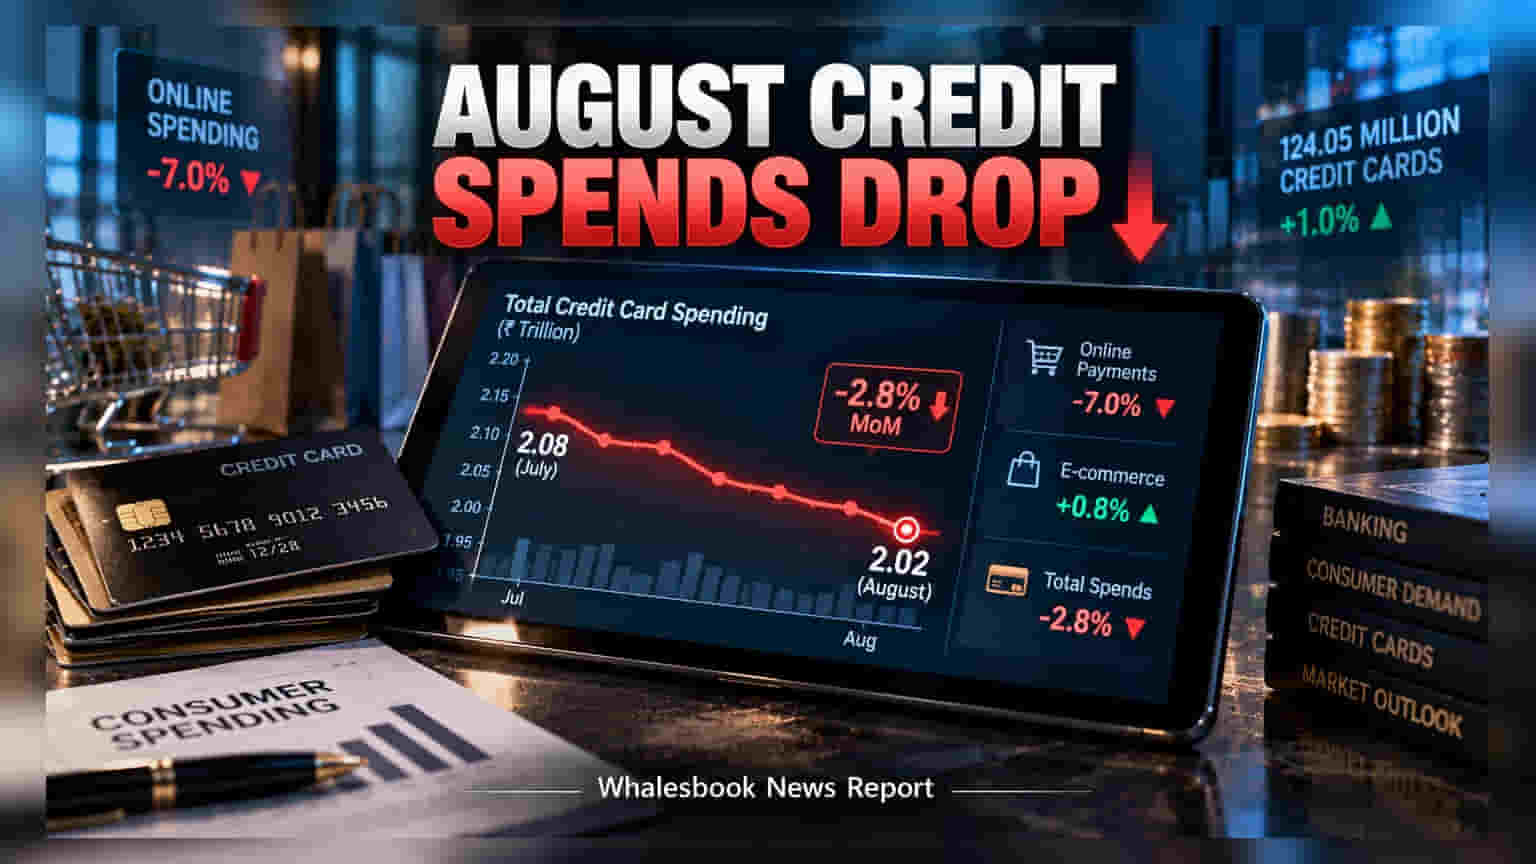
India’s credit card spending fell to ₹2.02 trillion in August, dragged down by a 7% slump in online transactions. While total card issuance grew to 124.05 million, major lenders like SBI Card and ICICI Bank saw transaction volumes decline. HDFC Bank remained resilient with a 1.83% rise in spending. This cooling trend in consumer usage is a key factor investors are tracking, as it may influence the short-term fee income of card issuers.
Credit card spending in India saw a broad deceleration in August, with total expenditure across the banking system falling to ₹2.02 trillion, compared to ₹2.08 trillion in July. According to the latest data from the Reserve Bank of India, the 2.8% month-on-month decline was primarily driven by a 7% drop in online payment volumes, which totalled ₹1.23 trillion for the month. While e-commerce specific spending showed a modest recovery, the overall contraction in digital transactions indicates a cooling trend in consumer spending patterns.
Divergent Performance Across Lenders
The impact of this slowdown was not uniform across all financial institutions. HDFC Bank, the market leader in credit card issuance, bucked the industry trend by reporting a 1.83% increase in spending, with total transaction value reaching ₹61,233 crore. This resilience contrasts sharply with other major players who faced a tough month. SBI Card, a dedicated credit card issuer, saw the most significant pullback, with spending on its cards sliding by 10.8% to ₹35,313 crore. Similarly, ICICI Bank and Axis Bank posted spending declines of 4.9% and 4.7% respectively, reflecting the broader pressure on consumer transaction activity at these institutions.
The Growth Paradox
While transaction volumes dipped, banks continue to aggressively grow their cardholder base. The industry added more customers in August, with the total number of outstanding credit cards rising to 124.05 million from 122.85 million in July. SBI Card led the expansion, adding over 193,000 new cards, while HDFC Bank added 122,669, taking its total base to 27.09 million.
For investors, this trend creates an interesting paradox: banks are acquiring new customers at a steady pace, yet the activity level per card has moderated. This suggests that while market share expansion remains a priority, the immediate revenue from transaction-based fees may face pressure if consumer caution persists. Credit card companies earn a significant portion of their revenue through interchange fees—a percentage of each transaction—meaning that lower spending volumes can directly impact this income stream.
What Investors Should Monitor
Moving forward, the primary concern for stakeholders is whether this decline is a seasonal blip or the start of a sustained period of reduced consumption. The upcoming festive season will be the next major test for the industry. Historically, festive months see a surge in consumer demand and spending. Investors will be watching whether this seasonal boost can reverse the August trend and drive higher transaction volumes, which would support the profitability of credit card issuers. Additionally, the asset quality of these lenders will remain a key focus, as any significant decline in consumer spending can sometimes act as a precursor to stress in credit card portfolios.