

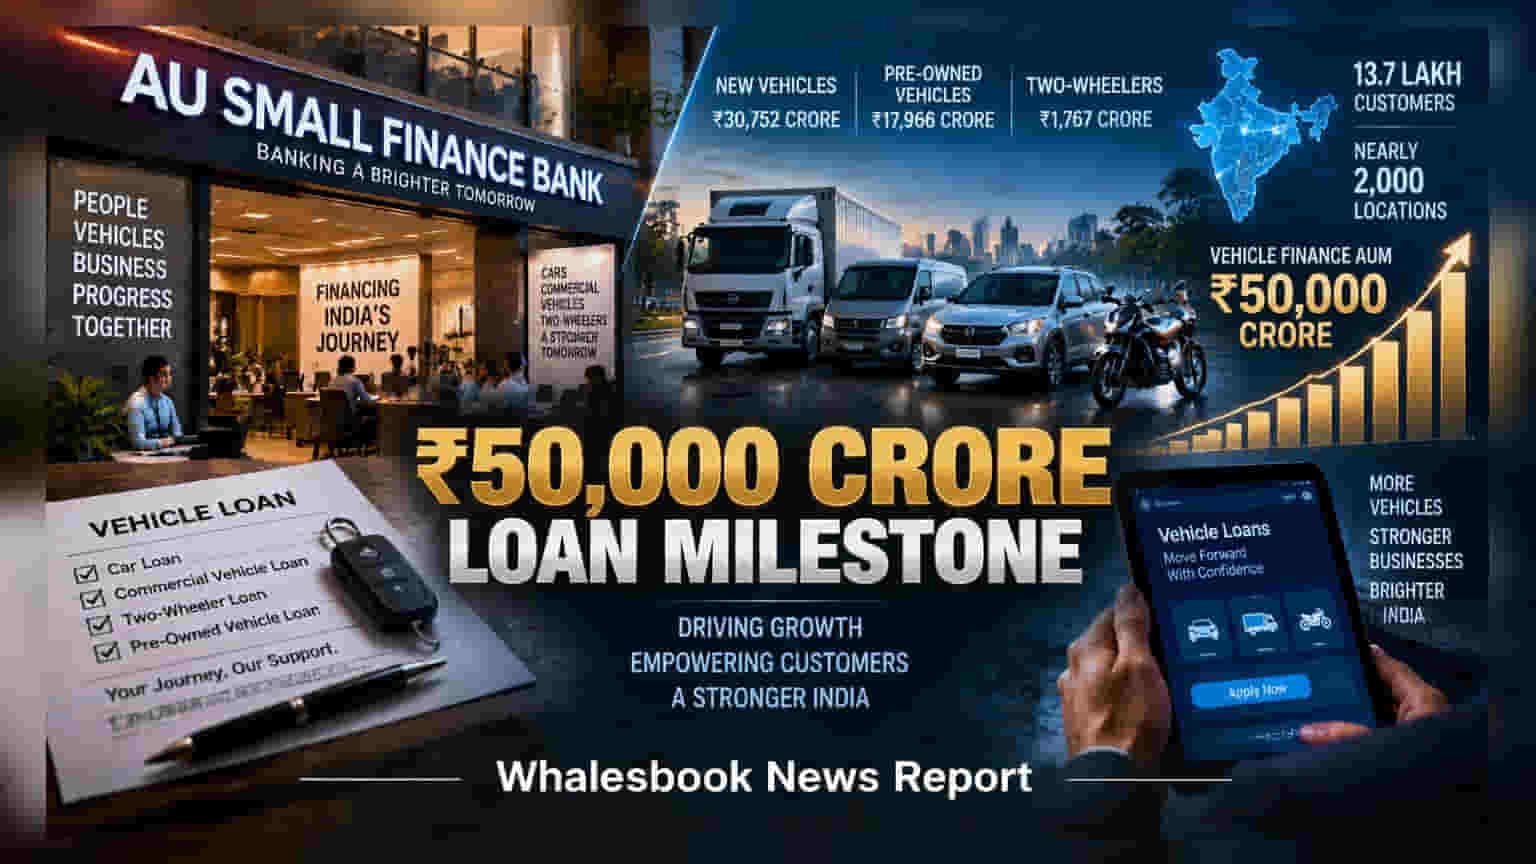
AU Small Finance Bank's vehicle loan portfolio has crossed the ₹50,000 crore milestone as of August 2026. This core segment, which accounts for one-third of the bank's total loan book, remains a primary growth engine as the lender prepares for its transition into a universal bank.
AU Small Finance Bank (AU SFB) has officially reached a significant milestone in its lending operations, with its vehicle finance portfolio surpassing ₹50,000 crore in assets under management as of August 2026. This division has long served as the foundational pillar of the bank’s business, consistently accounting for approximately one-third of its total loan book.
The scale of this achievement reflects deep penetration into the Indian vehicle finance sector, with the bank now serving over 13.7 lakh customers across nearly 2,000 locations. The portfolio is diversified across three main categories: new vehicle finance, which holds the largest share at ₹30,752 crore; pre-owned vehicle finance at ₹17,966 crore; and two-wheeler finance, which stands at ₹1,767 crore.
Historically, this segment has been a high-growth area for the bank, recording a three-year compound annual growth rate (CAGR) of 26% and a five-year CAGR of 29%. For investors, this performance is noteworthy because it highlights the bank’s ability to scale its legacy business even as it diversifies into other retail banking areas. The management has indicated that this vehicle finance franchise will continue to be a key driver of expansion as the bank moves forward with its strategic plan to operate as a universal bank, following in-principle approval from the Reserve Bank of India.
While the milestone showcases strong operational reach, investors should balance this growth with broader sector-specific monitorables. As the bank evolves, its financial performance will depend on how it manages net interest margins (NIMs) amid competitive pricing pressures and shifting deposit costs across the banking industry. Furthermore, the expansion into diverse retail lending segments requires a consistent focus on asset quality and prudent underwriting to mitigate credit risks. Operational integration during the transition to a universal banking license remains another area that market participants may track for potential execution impact.
The next important updates for shareholders will be the bank's quarterly financial results, which will provide insight into how this growth in the vehicle loan portfolio is impacting overall profitability and whether the bank can maintain its asset quality metrics while scaling these operations further.