

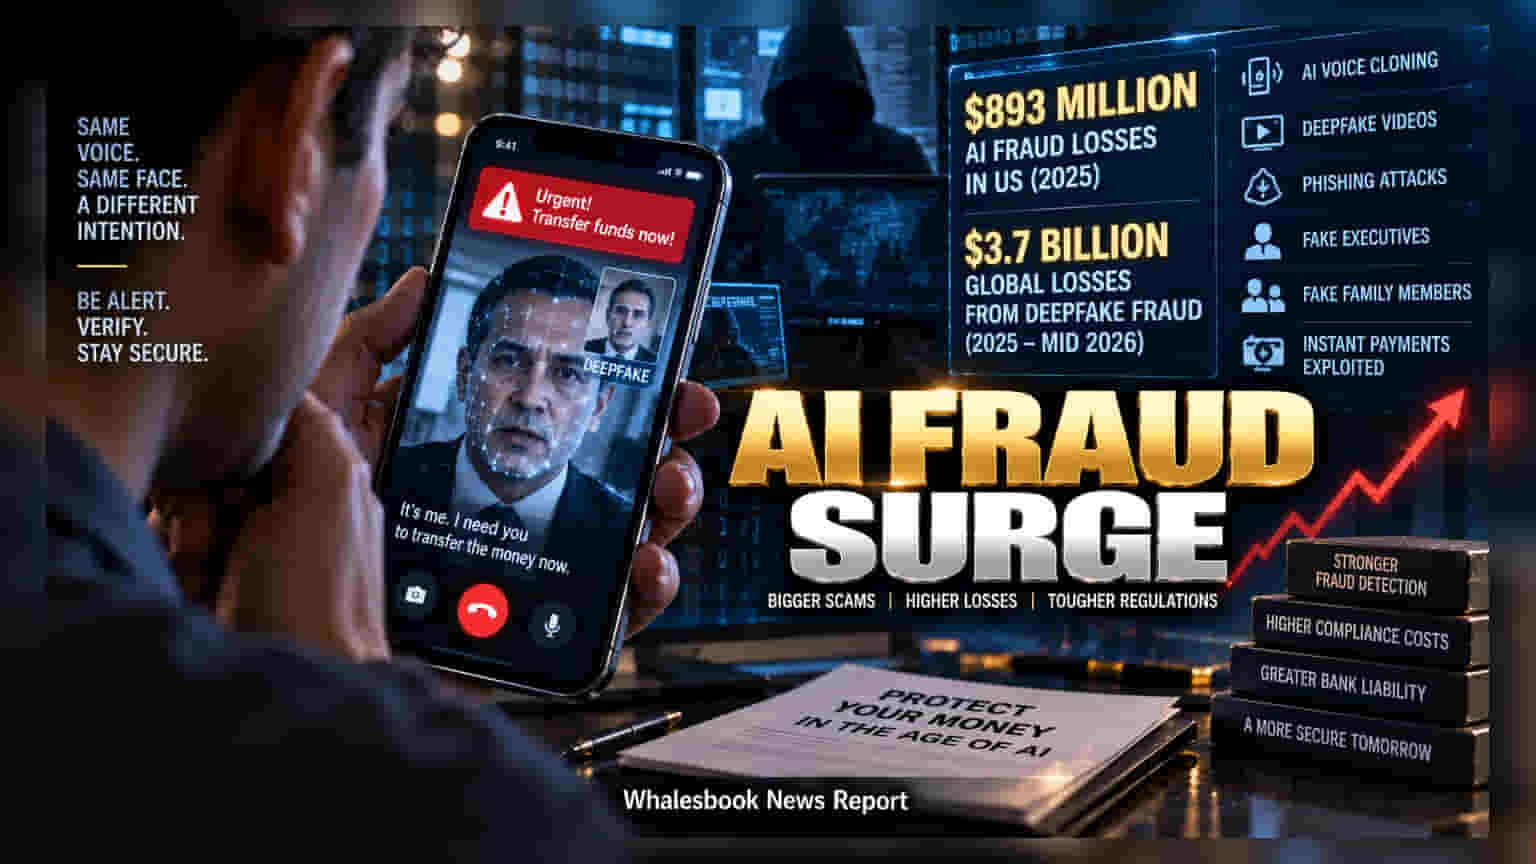
AI-driven financial fraud, including deepfake and voice cloning scams, has led to over $3.7 billion in global losses. As these sophisticated threats exploit digital payment systems, banks and financial institutions face mounting pressure to increase cybersecurity spending and navigate shifting regulatory liability models.
The rapid rise of artificial intelligence has introduced a new layer of risk for the global financial sector. In 2025 alone, FBI data linked over $893 million in financial losses to AI-enabled scams in the United States. Broader estimates, including studies by cybersecurity firm Surfshark, place documented global losses from deepfake fraud at approximately $3.7 billion, with the vast majority of these incidents occurring between 2025 and mid-2026.
Evolving Deception Tactics
Criminals are moving away from traditional, generic phishing methods toward highly personalized, AI-generated attacks. Using affordable software, fraudsters can clone voices from social media content or create convincing deepfake videos of corporate executives or family members. These tactics aim to exploit human stress and urgency. By simulating a crisis—such as a video call from a high-ranking official or a panicked relative—scammers force victims into making hasty financial decisions, often bypassing their rational judgment. This creates a significant challenge for individual retail users and corporate finance departments alike, where even a single successful breach can lead to massive fund transfers.
Systemic Risks in Digital Payments
Financial institutions are grappling with a dual challenge: the speed of modern payment networks and the increased sophistication of attacks. Many instant payment platforms are designed for convenience and rapid fund movement, which scammers exploit to move money out of reach before detection systems can flag the transaction. Furthermore, AI-driven bots are now used by criminal networks to test credentials against bank account systems at speeds that human teams cannot match. This creates a persistent, automated threat that requires banks to upgrade their security infrastructure continuously.
Regulatory Shifts and Liability
For investors, the most critical aspect of this surge is the potential change in regulatory liability. Currently, the regulatory landscape is fragmented. In many jurisdictions, banks often classify transactions as authorized if a customer is manipulated into initiating the payment, which frequently leaves the victim to bear the loss.
However, this model is under scrutiny. The United Kingdom has already implemented a liability framework requiring banks to reimburse many scam victims, which has compelled institutions to deploy more robust, network-wide fraud detection tools. As global fraud losses are projected by consulting firms like Deloitte to rise significantly, there is growing pressure on regulators worldwide to shift a greater portion of the financial burden onto banks and payment providers. For financial institutions, this could mean higher operating costs as they invest in advanced AI-based fraud detection systems to reduce liability and protect customer funds.
Investor Monitorables
Investors tracking the banking and fintech sectors may look for several key indicators in the coming quarters. First, companies will likely increase their capital spending on cybersecurity and AI-driven fraud detection, which could impact short-term profit margins. Second, any changes in banking regulations regarding customer liability for digital fraud could shift the cost burden directly onto financial institutions. Finally, the ability of banks to maintain trust through superior security measures will become a competitive advantage, as consumers increasingly prioritize platforms with stronger protection against sophisticated AI-based attacks.