

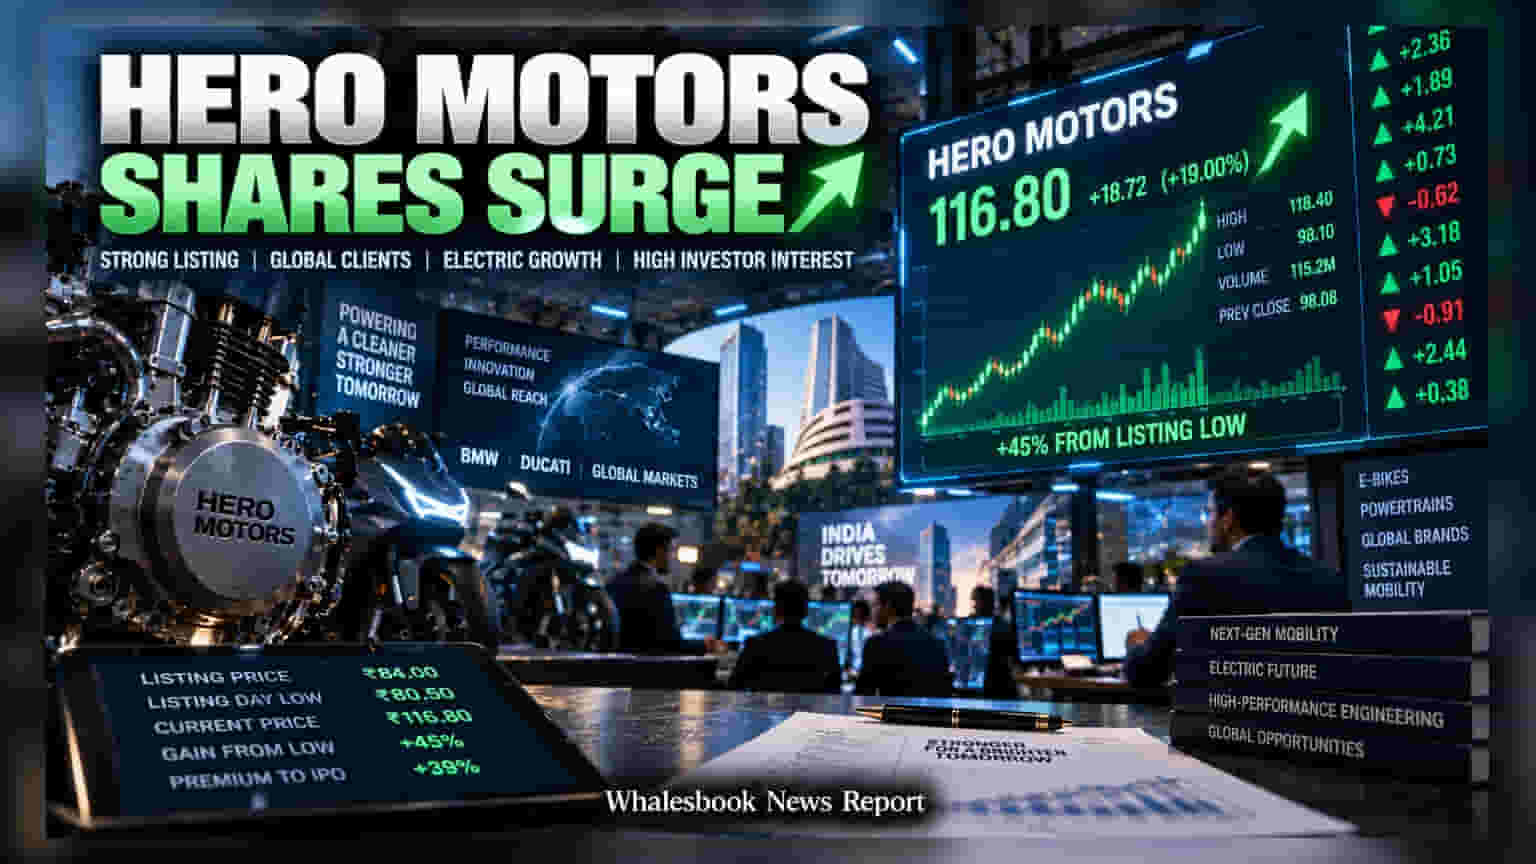
Shares of auto-tech manufacturer Hero Motors climbed 19% to ₹116.80 today, extending gains to 45% from their listing-day low. While investor interest in the company's high-performance powertrain business remains high, the stock trades at a valuation of approximately 74 times its earnings, with analysts flagging risks from heavy European market exposure.
Hero Motors shares recorded a sharp 19% gain to reach ₹116.80 on the exchange today. This momentum continues a strong run for the newly listed auto-tech company, which has seen its share price rise 45% from its listing-day low of ₹80.50 recorded on September 23, 2026. The stock is currently trading at a premium of about 39% compared to its initial public offering price of ₹84. While the broader market experienced a decline of 0.88% during the same session, Hero Motors has continued to see high trading volumes, with over 115 million shares changing hands.
The company specializes in designing and manufacturing powertrain solutions, particularly for high-performance motorcycles and e-bikes. Its business model is anchored in serving global marquee brands, including names such as BMW and Ducati. This specialized segment, along with the industry's broader shift toward electrification, has been a key driver of investor interest. However, the rapid increase in share price has outpaced the valuation estimates set during the IPO. Analysts have previously noted a valuation of approximately 74 times the company's estimated earnings for the 2026 fiscal year. This high valuation multiple indicates that investors are pricing in significant future growth, meaning the company will need to maintain consistent operational delivery to support these levels.
Investors are also balancing this growth story against specific structural challenges. A significant 34% of the company's revenue originates from European markets. This creates a reliance on the economic and geopolitical stability of the region, which can affect export demand and currency realisations. Furthermore, the company depends on a limited supplier base for essential raw materials. The absence of long-term supply contracts means that any global supply chain disruption or volatility in raw material costs could put pressure on the company's profit margins.
Moving forward, the primary factor for market participants will be the company's ability to navigate these international market dependencies and manage its supply chain. The consistency of order execution and sustained demand from its high-end global clients will be essential to track, as these will determine whether the business can justify its current market valuation.