

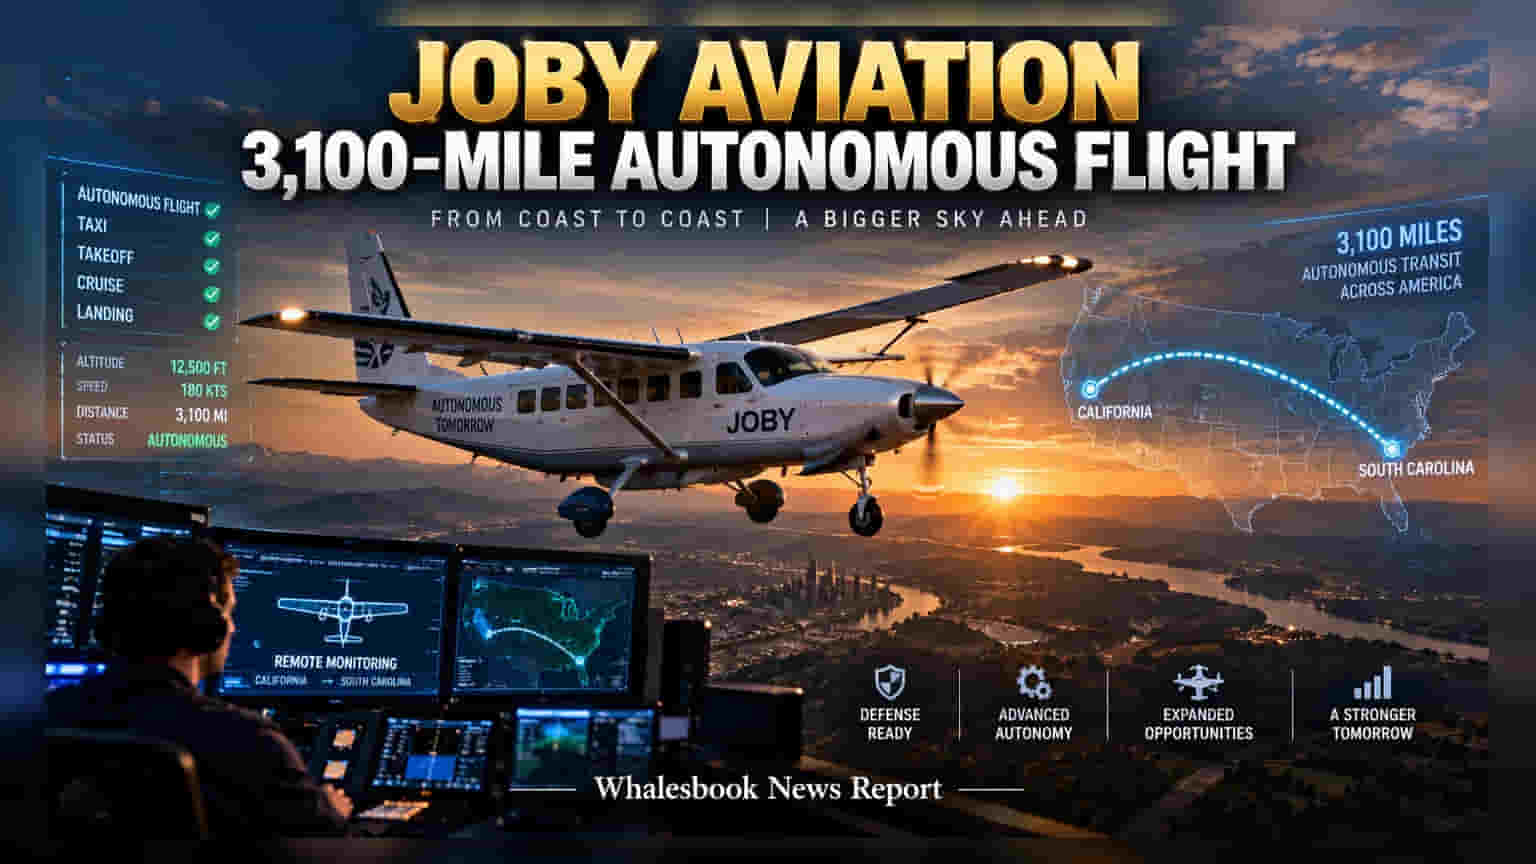
Joby Aviation completed a 3,100-mile autonomous flight using a modified Cessna Caravan, signaling a pivot toward defense and logistics. Following its $500 million acquisition of Resonant Sciences, the company is diversifying revenue streams beyond its passenger urban air taxi business. Investors may watch how this strategy impacts the company's cash reserves and path to commercial revenue.
Joby Aviation has successfully completed a 3,100-mile autonomous transit across the United States. The mission, conducted using a modified Cessna Caravan, demonstrated the company’s autonomy software's ability to operate outside of its primary urban air taxi environment. By retrofitting conventional aircraft with this software, the company is positioning itself to enter the defense and logistics sectors while it continues to work toward passenger service certification with the Federal Aviation Administration.
Strategic Shift to Defense
The flight included autonomous taxiing, takeoff, and landing, with remote monitoring conducted from California and the Shaw Air Force Base in South Carolina. While a pilot was present for safety and regulatory compliance, the aircraft operated autonomously throughout the trip. This capability validates the software stack that Joby is developing for military applications. The company has an ongoing $17 million contract with the U.S. Air Force under the AFWERX program and is also collaborating with L3Harris Technologies on hybrid-electric autonomous systems for military use.
This expansion into the defense sector is a significant change in business direction. In August 2026, Joby finalized the acquisition of Resonant Sciences for $500 million. This integration adds specialized radio frequency and sensor expertise to its defense division, providing a foundation for government and industrial contracting that operates on a different development timeline than passenger-focused air mobility.
Financial Context and Risks
For investors, the primary monitorable remains the company’s financial health. Like many firms in the advanced air mobility sector, Joby is currently in a pre-commercial phase for its primary passenger service, leading to high capital spending and cash burn. Diversifying into defense contracts may provide an alternative revenue stream, but execution risk remains high. The aerospace and defense sector requires strict adherence to government standards, and the company must manage its cash reserves while scaling these new operational capabilities.
Competition in the advanced air mobility space is also intense. Other players, including Archer Aviation and Lilium, are also pursuing various pathways to commercialization. Joby’s ability to successfully secure and execute defense contracts will depend on its software reliability and the integration of the newly acquired technology. Investors may track future updates on contract wins, the timeline for commercialization, and the company’s overall cash flow management as it balances its passenger taxi ambitions with new industrial and defense objectives.